Currently, there are dozens of valid reasons for closing one or more credit cards. Nevertheless, is it really a good idea? Will it affect your credit rating? In the next few lines, Milesopedia will share with you everything you need to know about the subject.
Understanding Your Credit Score Calculation: The Basics
First, remember that a credit score is a numerical picture of your current financial situation. The credit bureaus compile various information such as credit history and defaults to determine it on a scale of 300 to 900.
And how is this credit rating calculated? By reading the credit bureau’s advice articles, one can quickly deduce the main criteria of this calculation, as well as their importance:
Punctuality (35%)
This is the number 1 element in calculating your credit score. Are you paying off your balances to the minimum required each month? Do you do this before you receive your monthly statement? These actions are essential to optimize your rating.
Usage (30%)
Regardless of the line of credit (mortgage, line of credit, credit card, etc.), your utilization ratio should always remain below 30%. This ratio represents the amount of credit used, divided by the total credit available. So, if you use $2000 each month, on a total credit of $10,000, your ratio is 20%.
Historical (15%)
It is always recommended to keep a line of credit as long as possible. The movements at this level are all raised by the credit bureaus, which can interpret them as they wish (lack of funds, instability, etc.).
Credit applications (10%)
Every new credit application impacts your credit rating. Nevertheless, lost points are usually compensated within a few weeks. But, be careful: the ratio as well as the punctuality are important for the whole to balance.
Types of credit (10%)
Are you paying off your various sources of credit (personal loan, credit cards, line of credit, etc.)? If so, credit raters see this as proof of your reliability, and 10% of your credit rating benefits.
The impact of cancelling a credit card
As you’ll have understood, closing a credit card necessarily has an impact on your credit file, but not as great as you might think. Principles do exist. That’s why it’s crucial to weigh the pros and cons carefully before proceeding. Precisely, these two elements are affected:
1 – A gap in your credit history
Your credit history is a proof of your credit background. It is therefore valuable to you, since it shows your payment frequency, your credit ratio and other decisive elements of your credit use.
When you close a credit card, that account stops adding to your credit history. It doesn’t vanish right away: according to the FCAC, as of September 2026, a closed account in good standing stays on your report for up to 10 years with Equifax and up to 20 years with TransUnion. Once it drops off, your file loses that history, which can hurt in the long run.
Let’s take the following example:
You have two credit cards. One is 10 years old and the other is 3 years old. After careful consideration, two cards are too much for you and you decide to cancel the older one. In 10 years, the credit card you’ve kept will only be 13 years old. If you had kept the other one, she would be 20 years old. And that’s not to mention that by then, that history may already have dropped off your Equifax report.
Although both terms (13 years and 20 years) are excellent, a 20-year history is always more advantageous!
2 – Increasing your utilization ratio
Too often, closing one credit card leads to an increase in the credit ratio on another card. For example, if you use 20% credit on the card you just cancelled, will that percentage be transferred to your card where the ratio is 25%?
In this case, you end up with a ratio amounting to 45%, which is 15% higher than the recommended ratio. And, as we saw above, the use of your account card is important in the calculation of your credit score (30%).
The right steps to take
Is it possible to cancel a credit card without important consequences? Yes While this will systematically create some shockwave in your credit picture, there are steps that can be taken to mitigate its effects, such as:
Make this choice for you, not for your credit rating
If having multiple credit cards affects your debt load, it’s crucial to address it. That in itself is more important to you than your credit rating.
Pay the balance
Is there a balance remaining on the card you wish to cancel? It should always be paid in full, even before any closing process. If you don’t, the credit bureau may consider it a major default and change your credit rating accordingly.
Apply for a new card
Depending on the reasons for closing a credit card, it is a good idea to apply for a new card or request a limit increase on another card. This provides you with the same or similar credit limit as the original limit. Then, this allows your credit rating to be less affected for closing.
Options before you close a card
Closing isn’t your only option when a card costs too much or no longer gets used. Two approaches limit the effect on your credit file, and one situation calls for extra care.
Switch cards with the same issuer
If the annual fee is the problem, ask the issuer to move you to one of its no-annual-fee cards. Ask two specific questions: does the account stay the same, with its original opening date, and do you keep your credit limit? If so, the age of that account keeps counting. However, if the issuer asks you to close the card and apply for a new one, that’s a closure followed by a new credit application, which adds an inquiry to your file.
Lower the limit instead of closing
Lowering the limit keeps the account open, but it reduces your available credit. Your utilization ratio therefore goes up too, though less than with a closure. For example, with $1,500 in balances and $10,000 in total limits, including $4,000 on the card in question:
Before: $1,500 out of $10,000, or 15%
Limit lowered to $1,000: $1,500 out of $7,000, or about 21%
Card closed: $1,500 out of $6,000, or 25%
Newcomers: a short credit file
According to the Financial Consumer Agency of Canada, Canadian credit bureaus only collect information about your credit activity in Canada. Your credit history from another country isn’t included. With a few cards opened less than a year ago, each account carries a lot of weight in the length of your history and in your total limit. Waiting until your file is longer before closing a card reduces the effect.
The right choices for your needs
Cancelling a credit card is a process that requires careful consideration. Always ask yourself whether this activity is essential for good financial management.
Our valuationMilesopedia first-year estimateFirst-year valueAnnual fee rebated$150Total$150Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
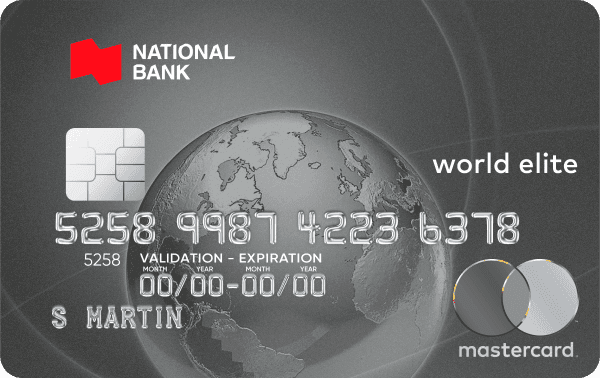
With Milesopedia, take advantage of an exclusive offer: your first-year annual fees are refunded with the National Bank World Elite Mastercard. This offer is exclusively available on the Milesopedia network, from June 30 to November 4, 2026.
Refund of the first-year annual fee (a $150 value) for the primary cardholder. This fee is charged to your new card account, then refunded as a credit on your statement within five months of opening your account, provided it remains open and in good standing.
The National Bank World Elite Mastercard is the best Mastercard credit card offered by NBC.
With this card, you earn up to 5 points per dollar on your purchases:
5 points per dollar for groceries and restaurants
2 points per dollar on gas and electric recharge purchases
2 points per dollar on recurring bills
2 points per dollar on À la carte Travel
1 point per dollar for all other purchases
And since it’s an NBC mycredit Mastercard, you can use it at Costco.
With this card, you have access to a $150 annual travel credit that you can use in any of these categories:
Airport parking
Baggage fees
Seat selection
Access to airport lounges
Airline ticket upgrades
What’s more, you can enjoy access to DragonPass airport lounges and unlimited access to the National Bank Lounge at Montreal-Trudeau.
Finally, Milesopedia has named the National Bank World Elite Mastercard as the Best Travel Credit Card in 2023, 2024, 2025, and 2026.
Legal
® Mastercard and World Elite are registered trademarks, and the circles design is a trademark of Mastercard International Incorporated. National Bank is an authorized user.
® The À LA CARTE REWARDS logo is a registered trademark of National Bank of Canada.
® NATIONAL BANK OF CANADA LOUNGE is a registered trademark of National Bank of Canada.
® À LA CARTE REWARDS PLAN is a registered trademark of National Bank of Canada.
® Apple Pay is a registered trademark of Apple Inc., registered in the U.S. and other countries. Apple Inc. is not a sponsor of or participant in National Bank Mobile Banking Solutions.
® Google Pay is a registered trademark of Google LLC. Use of this trademark is subject to Google Inc. Permissions.
TM À LA CARTE TRAVEL is a trademark of National Bank of Canada. The À la carte Travel agency is owned by Transat Distribution Canada Inc. and holds a Quebec permit (No. 753141).
TM À LA CARTE REWARDS is a trademark of National Bank of Canada.
® THE TOTAL, THE CONNECTED and NATIONAL BANK are registered trademarks of National Bank of Canada.
* Mastercard® World Elite®
The National Bank® World Elite® Mastercard® credit card was voted best Mastercard credit card by Milesopedia in 2026, 2025 and 2024.
The National Bank® World Elite® Mastercard® credit card was voted best travel credit card by Milesopedia in 2026, 2025 and 2024.
Every year, Milesopedia reviews credit card offers from major financial institutions and establishes its Ranking based on over 150 criteria such as fees, welcome offer, minimum income required, number of points per category, account credits, insurance, airport lounge access, etc.
Certain restrictions apply. For more information, see the Rewards Plan section or the Plan Rules applicable to point accumulation.
Grace period: No interest is charged on purchases made during the month if the cardholder pays the full balance of their account within twenty-one (21) days of the statement date. This grace period does not apply to cash advances and balance transfers. Minimum payment: if your account balance is less than $10, you must pay the balance in full. If you reside in the province of Quebec, your minimum payment is 5% of your account balance plus any overdue amount, or $10, whichever is greater. If you reside outside Quebec, your minimum payment is 2.5% of the credit card account balance plus any overdue amount, or $10, whichever is greater. Account statement: an account statement is sent monthly.
Table of examples of credit fees calculated over a 30-day period
Annual interest rate
$500
$3,000
22.49%
$9.24
$55.45
20.99%
$8.63
$51.76
13.2%
$5.53
$33.16
9.2%
$3.78
$22.68
*Variable interest rate in effect as of September 1, 2021.
Balance transfers and cash advances are subject to National Bank credit approval. Each amount transferred cannot be less than $250.
Exclusive to World Elite Mastercard cardholders. Presentation of the physical credit card and boarding pass is required to access the lounge. The National Bank® Lounge is accessible to customers traveling on international flights only (excluding flights to Canada and the United States). You benefit from free and unlimited access with one guest and two children aged 12 and under. Until October 4, 2026 (date subject to change), customers can enter the National Bank Lounge three hours before their flight departure time. From October 5, 2026 (date subject to change), access will be authorized for a maximum duration of 2 hours (3 hours for customers who hold a Private Banking 1859® World Elite® Mastercard® credit card). National Bank customers who are not World Elite ® Mastercard ® cardholders can also access the current lounge based on current rates and benefit from a 25 % discount on these rates : 63,24 $ taxes included for adults (excluding discount) $40.24 taxes included for children aged 2 to 12 (excluding discount) free for children under 2 (excluding discount) The entry fee is subject to change without notice and is the responsibility of the lounge operator.
Subject to providing the required supporting documents in the manner and within the prescribed timeframe. Certain conditions may apply. Only the primary cardholder of a National Bank World Elite Mastercard (Cardholder) whose account is in good standing can request a « Travel Fee Reimbursement ». « Account in good standing » means an account linked to the credit card that does not violate the Credit Card Agreement in any way and on which no restrictions apply. For example, and without limitation, the associated annual fees must have been paid in full. The maximum reimbursement of $150 can be requested from January 1 to December 31 of each year. Eligible expenses are: airport parking baggage fees seat selection airport lounge access worldwide airline ticket upgrades A reimbursement request must be made within 60 days of the purchase date. Travel expenses must be charged to the National Bank World Elite Mastercard credit card account. The maximum reimbursement of $150 is applicable per account. Please allow up to 7 business days for the reimbursement to be processed from the date your request is submitted. National Bank reserves the right to request additional supporting documents for validation purposes (e.g., invoices). You must keep all receipts and supporting documents for a period of 12 months from the date you made your reimbursement request. An unused reimbursement in one year cannot be carried over to the next year. You can make your request online at rewards.nbc.ca or by calling 1-800-341-8083 (toll-free) for an agent to assist you with your travel fee reimbursement request.
Point accumulation on grocery and restaurant spending depends on the total gross monthly amount charged to the credit card account, across all categories. Earn 5 points per dollar spent on eligible grocery and restaurant purchases. The 5 points per dollar accumulation is valid for the first $2,500 of gross monthly purchases charged to the account. Beyond this amount, eligible grocery and restaurant spending will earn 2 points per dollar. The calculation of the gross monthly purchase amount is based on monthly billing. A grocery purchase means a purchase made at a merchant whose primary business is selling food, such as a grocery store, delicatessen, supermarket, fruit store, or specialty food store. Meal kit subscriptions and meal delivery services are eligible. Therefore, this definition excludes, among others, retail stores and big-box stores whose primary business is selling non-food items. Some merchants may sell products or services identical or similar to those of eligible merchants, or are separate merchants located on the same premises as eligible merchants, but are classified by Mastercard in different categories. Purchases made from other merchants only earn base reward points. A restaurant purchase means a purchase made at a restaurant, including quick-service restaurants, bars, discotheques, nightclubs, and taverns. To view the full list of Mastercard codes associated with eligible merchants, download the À la carte Rewards Plan® terms and conditions document.
These protections apply if the purchases or rental are paid for in part with the card before departure, except, if applicable, for out-of-province medical-hospital insurance for which it is not necessary to charge the purchase of an à la carte trip and for baggage delay protection where the full cost of transport must have been charged to the card. All these protections apply to the primary cardholder, their spouse and/or their dependent children when they (spouse and dependent children) travel with the cardholder. Extended warranties apply to most new items purchased with the card, in Canada or abroad, provided the manufacturer’s warranty exists and is valid in Canada. Certain conditions, limitations and restrictions apply. For more information and details regarding your insurance coverage, please consult the insurance certificate linked to your card.
Subject to credit approval by National Bank.
Certain conditions apply. Visit mastercard.ca for more information. See all credit card terms and conditions.
To earn 2 points per dollar spent, you must pay for your gas or electric charging purchases at a gas station or certain big-box stores. Some merchants may sell products or services identical or similar to those of eligible merchants, or are separate merchants located on the same premises as eligible merchants, but are classified by Mastercard in different categories. Purchases made from other merchants only earn base reward points. To view the full list of Mastercard codes associated with eligible merchants, download the À la carte Rewards Plan® terms and conditions document.
Recurring bill payments are defined as payments made monthly or regularly that are automatically charged by the merchant to your National Bank World Elite Mastercard. Not all merchants offer recurring payments, and not all recurring payments are considered recurring bill payments. Therefore, some payments may not qualify for accelerated reward points.
To earn 2 points per dollar spent, you must pay for your eligible purchases through the À la carte TravelTM agency section of our À la carte RewardsTM site.
For example, if you spend $400 monthly on groceries, $200 on gas, $100 on recurring bills and $150 on other purchases, the $850 spent will generate 2,750 points, broken down as follows: 2,000 points for grocery spending (since the total gross monthly amount is $850, which is less than $2,500), 400 points for gas spending, 200 points for recurring bills and 150 points for other purchases.
Insurance up to $1,000 in case of breakage, loss or theft of mobile devices for a maximum period of 2 years following the date of purchase. Subject to purchasing the device with the National Bank World Elite Mastercard or a phone service subscription paid by recurring payments from your National Bank Platinum Mastercard starting September 1, 2022. For all conditions, please consult the insurance certificate linked to your card.
Annual fee
Primary card$150
Additional card$50
Annual income required
Individual$80,000
Household$150,000
Conversion fees
2.5%
Earning rate
5xRestaurants
5xGroceries
2xGas & EV
2xBills & recurring payments
2xTravel
1xAll spending
Value
1st Year Value$778
2nd Year Value$923
Card benefits
Airport lounge access$400
Travel creditsIncluded
Travel insurance
Travel medical (under 55)Up to $5,000,000 / 60 days
Our valuationMilesopedia first-year estimateFirst-year valueWelcome bonus$469Annual fee rebated$120Total$589Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
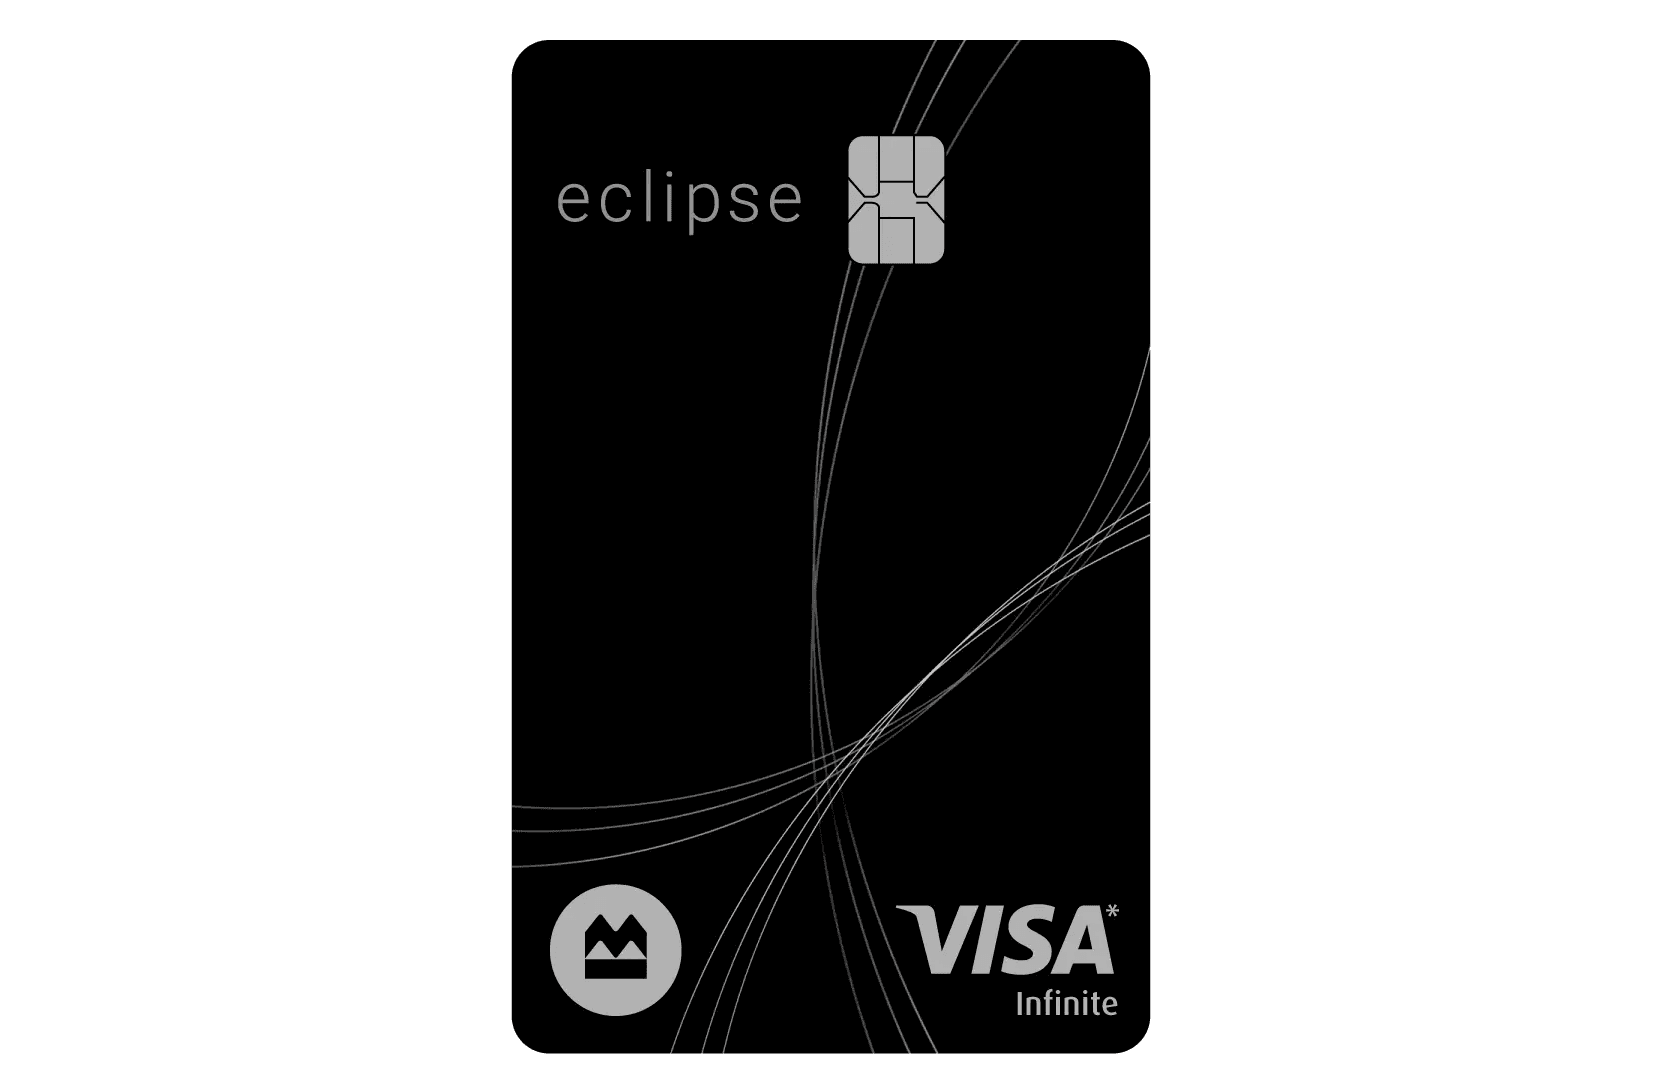
The BMO eclipse Visa Infinite* Card is one of the best Visa Infinite rewards credit cards in Canada. Its welcome offer lets you earn up to 70,000 BMO Rewards points, for a total value of up to $1,150*.
It also includes a monthly statement credit for streaming services, an annual $50 lifestyle credit, and no annual fee for the first year (a $120 value)*.
With the BMO eclipse Visa Infinite* Card, you also get:
5x BMO Rewards points for every dollar spent on groceries, meal delivery or takeout, rideshare, public transit, and gas*
1 BMO Rewards point for every dollar spent on all other purchases*
10% more points when you add an authorized user to your account*
Mobile device insurance offering coverage up to $1,000*
The Pay with Points feature, which allows you to redeem your points on recent purchases starting at $1*
Six months of Instacart+ membership plus a monthly $10 Instacart credit with an eligible card*
Legal
*Terms and conditions apply
BMO is not responsible for updating the content of this site. For the most up-to-date information, please click on the Online Application link.
Annual fee
Primary card$120
Additional card$50
Annual income required
Individual$60,000
Household$100,000
Conversion fees
2.5%
Earning rate
5xTransit
5xGas & EV
5xRestaurants
5xGroceries
1xAll spending
Value
1st Year Value$1,128
2nd Year Value$365
Travel insurance
Travel medical (under 55)Up to $5,000,000 / 21 days
Travel medical (55-64)Up to $5,000,000 / 21 days
Travel AccidentUp to $500,000
Purchase protection
Purchase ProtectionIncluded
Extended Warranty+1 years
Mobile DeviceUp to $1,000 / 1 years
Auto Rental CollisionUp to $65,000 / 48 days
Our editorial integrity
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.