Using Credit Card Cash Advances Wisely
Loading article…
A credit card cash advance can look like quick cash when you need short-term liquidity. But the term covers two very different things, and mixing them up is where people get burned.
On one side, a standard cash advance (an ATM withdrawal on your card) is one of the most expensive ways to borrow. On the other hand, issuers often run promotional balance transfer offers, sometimes 0% to 0.99% for 6 to 18 months, that can be useful if you understand the terms. This article explains the difference, the true cost, safer alternatives, and how to use a promotional offer wisely.
A cash advance is borrowing money directly from your credit card’s limit. The most common form is withdrawing cash from an ATM, but balance transfers, money orders, and convenience cheques are also treated as cash advances.
It’s convenient because you get the money almost instantly. The problem is the cost, which is rarely spelled out clearly. So let’s break it down before looking at when it can actually make sense.
A standard cash advance is not like withdrawing your own money from a debit card. Four costs make it expensive:
Bottom line: a standard cash advance is best avoided unless you’ve exhausted other options. The useful tool for most of the strategies below is something different: a promotional balance transfer offer.
Several issuers run low-rate promotions on balance transfers. They usually take one of these forms:
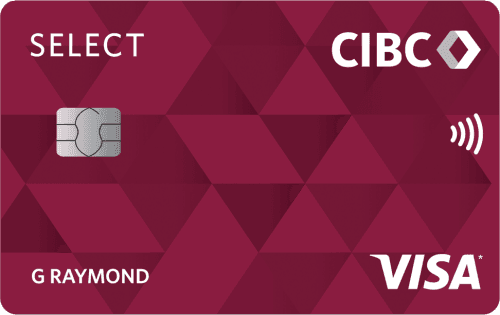
Each offer has its own term, rate, and fee, and may be available to new or existing customers. For example, new clients can sign up for the CIBC Select Visa* Card, which currently offers 0% interest for up to 10 months with a 1% transfer fee (no fee for Quebec residents) and a two-year annual fee rebate.
on CIBC's website
Some issuers also provide promotional access cheques that draw on this low promotional rate rather than the costly standard cash advance rate. Always confirm the rate, fee, and term in writing before you use one.
When the rate is genuinely low, and you have a clear plan to repay before it ends, a promotional balance transfer can buy you time or a small return. Here are three common uses, each with its caveats.
If you borrow at 0% and park the money in a high-interest savings account, the spread is yours, minus the transfer fee and minus tax on the interest. As of June 2026, savings rates are more modest than a couple of years ago: EQ Bank pays around 2.75%, while Tangerine runs promotional rates near 4.50% for new deposits over a limited window.
Here’s a simplified illustration of a $15,000 transfer at 0% for 10 months, parked at about 3%:
| Details | Interest or fees |
|---|---|
| 1% balance transfer fee on $15,000 | – $150 |
| Savings account (~3% for 10 months) | + $375 |
| Net return (before tax) | + $225 |
Promotional rates like Tangerine’s 4.50% for 5 months can boost the first months, but they drop afterward (to 0.30% in this case), so for a longer 0% term a steady rate like EQ Bank‘s ~2.75% may net more.
If you choose a notice savings account (like EQ Bank’s), remember you must give advance notice (usually 10 to 30 days) before withdrawing at the top rate. Trigger that notice well before your 0% repayment date, otherwise you could miss the deadline and have the balance revert to the standard interest rate.
Two reality checks: the interest you earn is taxable, and savings rates can drop during your term, especially teaser rates that reset after a few months. The upside here is modest, so the plan only works if repayment is certain.
If you have room in your RRSP, a promotional transfer can let you contribute before a deadline and benefit from a tax refund, while you earn the money to repay over the promo period. Borrowing to maximize your RRSP and get an income tax return is relatively common; a credit card cash advance is just another way of borrowing money.
The same logic applies to a child’s RESP (for the government grant) or your FHSA, both time-sensitive.
Keep one thing in mind: once money goes into an RRSP, you can’t pull it out freely like a regular savings account. You’re using borrowed time, not free money, so your repayment plan has to be solid.
Timing and evaluating your earning/saving potential are therefore crucial. For example, if you use the promotional balance transfer from the CIBC Select Visa* Card to contribute to your RRSP in October 2026, you will:
If you’ve just moved, renovations and furnishing costs add up fast. Instead of leaning on a line of credit at the prime rate, a 0% promotional transfer can cover purchases temporarily. When the promo ends, you can move any remaining balance to your line of credit, where the rate is usually lower than a card’s standard rate.
Similarly, if you’re carrying a balance on a higher-rate card, transferring it to a 0% or low-rate promo gives you breathing room to clear the debt faster, as long as you stop adding to it.
A standard cash advance should be a last resort. Before using one, consider these options:
If you do need to borrow on a card, these options keep the damage low. Rates and offers are current as of June 2026; confirm the details on each card’s page before applying.
| Card | Promotional offer | Cash advance rate | Annual fee |
|---|---|---|---|
| CIBC Select Visa* Card | 0% on balance transfers for 10 months (1% fee) | 13.99% | $29 (rebated 2 years) |
| Scotiabank Value® Visa* Card | 0.99% on balance transfers for 9 months (2% fee) | 13.99% | $29 (free year 1) |
| BMO Preferred Rate Mastercard®* | 0% on balance transfers for 18 months (2% fee) | 15.99% | $29 (free year 1) |
| National Bank Syncro Mastercard | Low ongoing rate (prime-based) | around 12.9% | $35 (free year 1) |
on Scotiabank's website
on CIBC's website
A standard credit card cash advance is expensive: high interest from day one, fees, and no rewards. Treat it as a last resort, after an emergency fund, line of credit, or overdraft.
A promotional balance transfer is a different tool. Used with discipline, it can buy time, help clear higher-rate debt, or earn a modest return, but only if you repay before the rate reverts. It’s borrowed money, and you must pay it back. When the numbers and the plan are solid, the upside is real; when they aren’t, the costs add up fast.
It’s borrowing against your credit card’s limit, most often by withdrawing cash at an ATM. Balance transfers, money orders, and convenience cheques are also treated as cash advances.
Interest starts immediately (no grace period), usually around 22.99% or more, plus a per-advance fee and any ATM fees. Cash advances also earn no rewards.
They’re related but not identical. A standard cash advance is charged the high cash advance rate immediately. A promotional balance transfer can run at 0% to 0.99% for several months, which is what makes the strategies in this article possible. Always confirm which rate applies.
No. Cash advances and balance transfers don’t earn rewards, and they don’t count toward a welcome bonus’s minimum spend.
For balance transfers, the CIBC Select Visa* Card (0% for 10 months) and BMO Preferred Rate Mastercard®* (0% for 18 months) lead as of June 2026. For ongoing low rates, the Scotiabank Value® Visa* Card and National Bank Syncro Mastercard are strong options.
Yes. An emergency fund, a line of credit, or overdraft protection are usually cheaper than a standard cash advance. Tapping a TFSA can also be less costly than borrowing at 22.99%.
on BMO's website
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.