

How Reward Points Work: Retail, Interchange, Bonus Points, Exclusions

Understanding how points are calculated helps you avoid pitfalls, but also take advantage of certain loopholes inherent in the limits of the parameters used for calculations.
The transaction you just made at IGA with your Scotiabank Visa Infinite + Passport Card may seem simple, but IGA and Scotiabank do not have the same information to credit your Scene+ points, and the number of points credited will likely be different on your two statements.
In this article, I would like to show you the nuances you need to know about points.
Merchant points
Whether you shop in-store or online, when a merchant credits you points on your purchases, they have a lot of information about what you bought, starting with the details of each item on your receipt.
Exclusions
Because they have access to the transaction details, a merchant can exclude certain line items when calculating the number of points earned. Often, the same exclusion rules also apply to senior discounts and employee discounts.
Exclusions are something you must absolutely keep an eye on, even if that means reading the fine print. There are several categories of exclusions, each with its own history and rules of application.
Exclusions related to laws and regulations
Some products cannot be discounted by laws or regulations. This legally prevents the merchant from giving you points on these products.
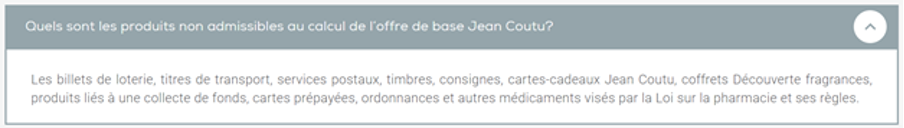
This exclusion category also includes:
- tobacco
- lottery tickets
- and even in some cases products where floor prices apply, such as milk or beer.
Fees and taxes
The merchant may also decide to exclude certain line items in the transaction on which they earn no (or very little) profit margin. For example:
- taxes,
- delivery costs,
- bottle depots,
- tips.
Example: Aeroplan and Uber Eats

Category exclusion
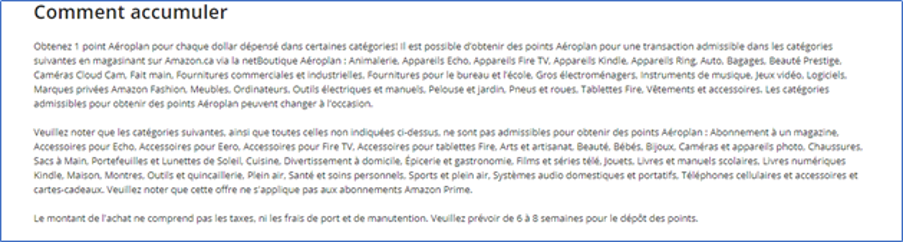
The merchant may also specifically include or exclude product categories/ranges.
The main reason is that the business does not make enough profit margin on the sale, for example public transport tickets, stamps, etc.
Example: Aeroplan and Amazon
Gift card exclusions
For a merchant, there is a big difference between selling a gift card from another brand (e.g., a Netflix or Amazon card) and a gift card for its own brand.
In the first case, it is a product like any other, and the store will earn a margin (between 5% and 15%) on the sale.
In the second case, the store will not make any money on the transaction; it will simply receive payment from the customer, which it will exchange for an “acknowledgement of debt” (a gift card) and place that amount in trust (the clearinghouse).
When the customer uses their gift card, the merchant will make its profit on the sale of goods and will be paid with the money held in trust.
This is why, in most cases, the two purchases are not treated in the same way.
Exclusion from the transaction
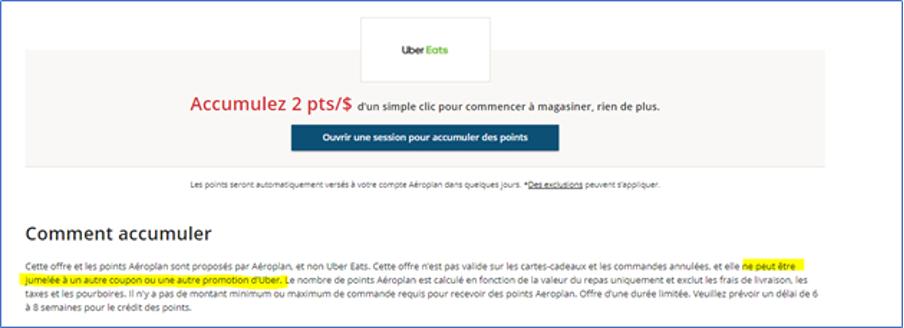
Finally, the merchant may decide to exclude the transaction entirely under certain conditions. For example, if a coupon is used, another promotion applies, or the transaction is already subject to a bill discount such as an employee purchase or a seniors discount.
This is the case for Uber Eats when using the Aeroplan eStore.
Example: Amazon and Uber Eats
The calculation of the base points
Earning rate
Base points are calculated on the transaction once exclusions are removed, and once discounts are applied (i.e. promotions, employee discounts, etc.).
The amount calculated this way will be used to establish the number of points you will receive for the transaction according to the scale pre-set by the program for this merchant.
Earning scale
Each loyalty program has its own currency, and as with foreign currencies, each currency has its own value: for example, a PC Optimum point does not have the same value as an Aeroplan point or a Scene+ point.
So each program will award points based on the currency value it uses.
Some programs have a very strong currency and offer only 1 point per $10, $20, or $25, while other programs offer a weaker currency, going as far as awarding 100 points per $1.
Example of currencies and earning rate
| Currency | Approximate value | Earning example for a $100 purchase |
|---|---|---|
| Aeroplan | 2 cents | 100 points |
| PC Optimum | 0.1 cent | 1,000 points |
| Scene+ | 1 cent | 100 points |
However, most programs have opted for a base earn rate of 1 point per $1.
Rounding up
Each program (and merchant) has its own rounding method when calculating the number of points you should receive.
The majority of the programs will however use a rounding down and therefore to the advantage of the merchant.
For example, if all your purchases add up to $39.99 and the basic bonus is 1 point/$1, you will get 39 points, whereas if the accumulation is 1 point/$20, you will only get 1 point for this transaction.
And if your transaction is only $19.99, in the first case you will receive 19 points, whereas in the second case you will receive no points.

- Annual fee
- $191.88
- Our valuation
- $255Milesopedia first-year estimate First-year valueWelcome bonus$255Total$255Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Milesopedia first-year estimateFirst-year valueWelcome bonus$255Total$255Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Welcome offer
- Up to 15,000 points
on American Express's website
Apply with confidence — no impact on your credit scoreApply with confidenceCheck whether your application will be approved before you submit it, with no impact on your credit score*When you apply for a personal American Express Credit Card, we will tell you whether you are eligible without affecting your credit score. So you can apply with confidence.*Instant decisions are only available for consumer Card applications (also called “personal Cards”).
Bonus points
The merchant may decide to apply a bonus (often temporarily) to the entire transaction, to a category of products in the transaction (e.g. cosmetics) or to specific products.
These bonus points are often linked to a specific campaign, and for campaign analysis and investment reasons, they are often counted separately from base points.
Multipliers
When the points on a transaction (or a category or a product) are multiplied, the principle is always the same: there is what the advert says (10x the points) and how this will be translated on the statement, i.e. the base points and a bonus to get 10x (so 9x the base).
For example: if we have a $100 transaction and the regular earn rate is 1 point per $1, then the statement will show 100 base points and 900 bonus points for a total of 1,000 points (i.e., 10x the base bonus of 100 points).
Bonus points on products
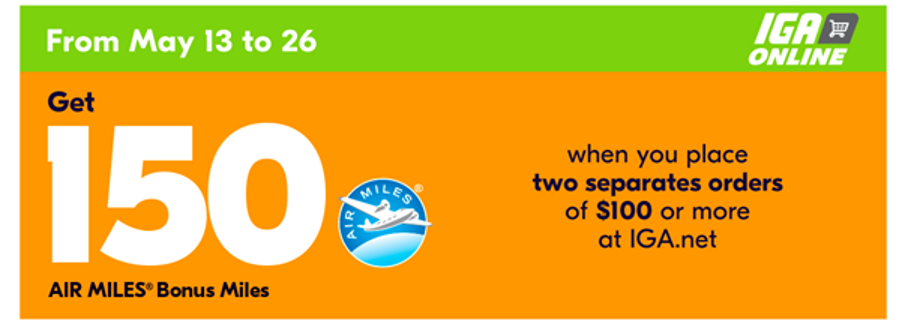
You may also see promotions in the form of bonus points on specific products (e.g., 5 AIR MILES), in which case the bonus is triggered when you buy the specific product and is added to the points you earn on the total transaction amount.
Bonus points on transactions
There are also promotions that trigger after a certain spending threshold, with the goal always being to push you above that threshold.
Example: if the average grocery cart is $80, why not force the purchase of a few more products by offering a few extra points when the customer exceeds $100.
Questions
Are the promotions cumulative?
In most cases the answer is yes, but perhaps not as cumulative as we would like to think.
To simplify the example, we will use a base offer of 1 point/$1.
For example, if there is a 5x points promotion, and at the same time I have a coupon that gives me another 10x points after $100, and finally I buy 10 products at $10 that give me 50 additional points per product, how many points will I have in total?
Note: unfortunately the answer is not 30,000 points (100+10 x 50) x 5 x 10
Is a bonus of 10x points good?
A 10x points offer is always better than no additional bonus.
In fact, the real question is:
- Are all 10x worth the same?
- Is a 10x AIR MILES promotion really better than a 3x Aeroplan?
Example parameter:
- A merchant available on the AIR MILES Shop and the Aeroplan shop (ex: Etsy)
- Basic offer
- AIR MILES: 1 AIR MILES bonus miles per $20
- Aeroplan: 1 Aeroplan point per $1
Currency valuation
- AIR MILES: 10.5¢
- Aeroplan point: 1.7¢
Promotional offer
- AIR MILES: 10x miles
- Aeroplan point: 3x points
What is the best offer?
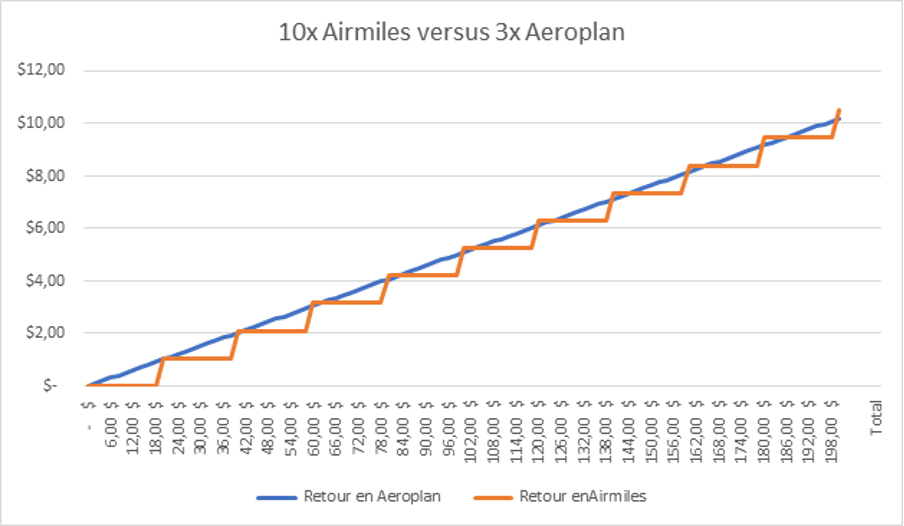
Yes, it is counterintuitive, but in most cases with the same merchant, a 10x AIR MILES promotion is less “interesting” than a 3x Aeroplan points promotion.
This is due to the bonus structure and the « rounding up ».
Credit cards points
In the case of credit cards, the “product” on which points are awarded is not what is in your cart but the “payment solution,” meaning what the merchant will pay in fees to be able to collect the money from the transaction: interchange fees.
When you receive points via your credit card, the card issuer has far less information than the merchant to calculate the number of points it must credit.
The myth of Level 3 information / Level 3
Let us immediately debunk a myth: in Canada, the credit card issuer does not have access to the contents of the cart (the « Line Item Detail of Purchase »).
Even though Level 3 information transfer (Level 3 processing) exists in theory, it does not apply to our Canadian credit cards (unlike U.S. credit cards).
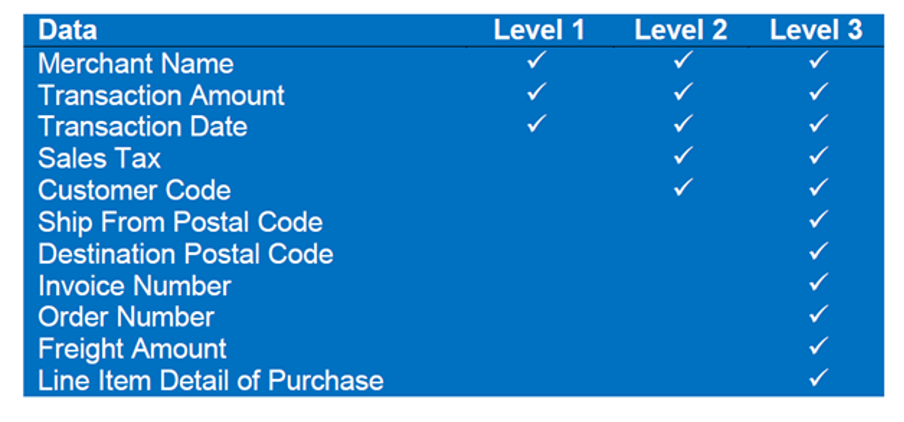
The vast majority of information transmitted is Level 2 (« Level 2 ») between the merchant and the card issuer.
Indeed, two conditions must be met for the credit card issuer to have access to the famous Level 3, which contains the information for each product purchased in a transaction (“Line Item Detail of Purchase”).
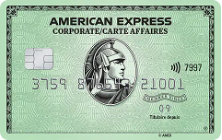
Condition 1: It must be a “corporate” credit/payment card. These cards are not available to the general public; they are different from SME or personal cards and are intended for large companies or government organizations.
Condition 2: The store must support Level 3 information transfer. We will not go into the details, but it is an investment for the merchant that it can only recoup if it processes a lot of corporate card transactions (mainly by saving on interchange fees for those transactions).
Exclusions
In the case of a credit card, exclusions and calculations are therefore done at the transaction level.
As when a merchant credits points, some transactions may be excluded.
Exclusions are mainly as follows:
- Interest charges
- The card ‘s fees
- Cash advances (e.g. ATM withdrawals)
- Payments on online casino platforms (e.g., Loto-Québec),
- Payments on international money transfer platforms, currency purchases.
In addition, certain clauses may apply, such as those for American Express:
- Transactions processed manually or using a paper-based process (for example, transactions processed using a credit card imprint);
- Purchase for which the merchant category is not defined.

- Annual fee
- $150
- Our valuation
- $350Milesopedia first-year estimate First-year valueWelcome bonus$350Total$350Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Milesopedia first-year estimateFirst-year valueWelcome bonus$350Total$350Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Welcome offer
- Up to 35,000 points
- Ends Nov 1, 2026
on Scotiabank's website
The calculation of the base points
Unlike the merchant side, when calculating a transaction, it is the entire transaction that is eligible or not.
So, for example, at a restaurant, the total amount paid, including taxes and tip, is what will be sent to the card issuer and therefore what the calculation is based on.
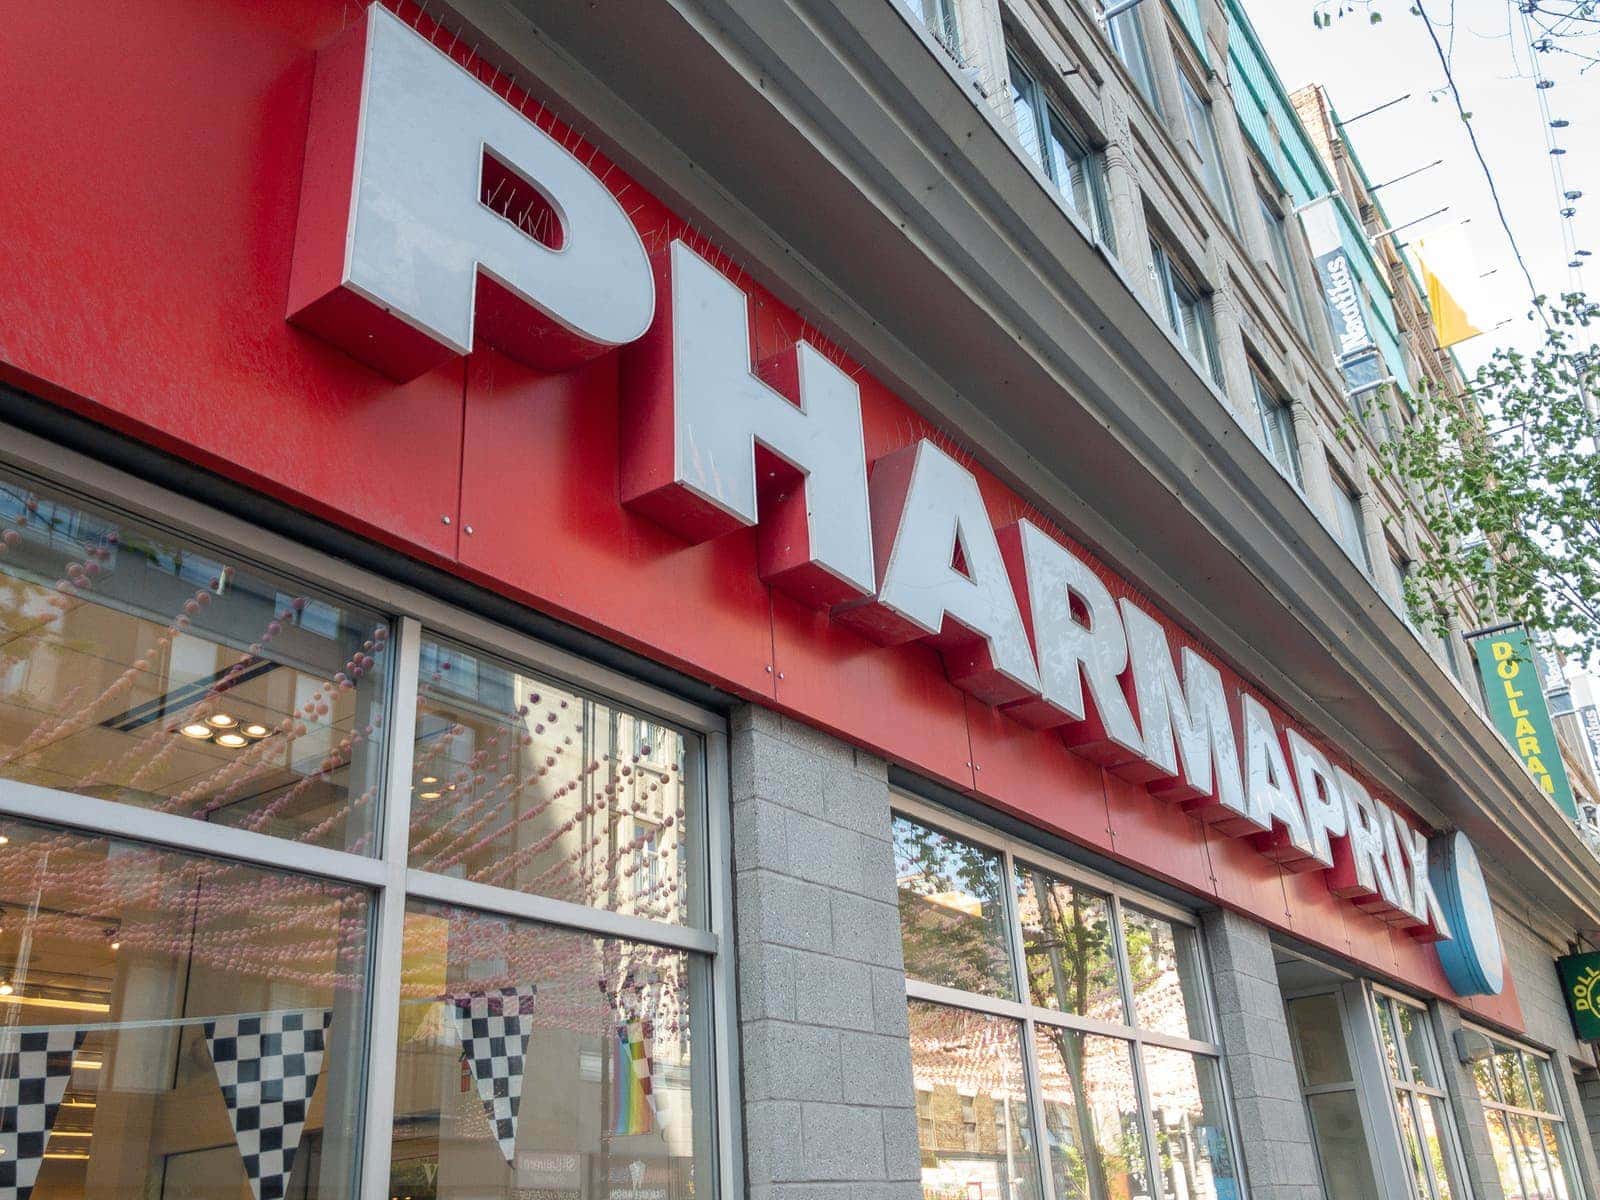
For the same reason, you can therefore earn points via your credit card on medication purchases even in Quebec.
Bonuses by type of purchase
Often certain types of purchases will earn you extra points.
To do this, the issuer will use the information it receives from the merchant to determine whether the transaction qualifies for an additional earn rate (2x, 4x, 5x), whether for a specific merchant (Apple, Amazon, Expedia, Petro-Canada, Ultramar, Walmart, Marriott, etc.) or for a type of merchant (Grocery, pharmacy, gas station, travel, etc.).
Merchant Category Codes
The Merchant Category Code (MCC) is a standard for categorizing what a business sells.
MCC codes exist in two forms: codes identifying the category of the store (5912: Pharmacies) or in the travel field, codes with the name of the company directly (3007: AIR FRANCE).
There are about 1,000 different codes to classify businesses. For example, there are two codes for restaurants (5812: Eating places and Restaurants, and 5814: Fast Food Restaurants) as well as a specific code for Bars (5813).
Communication between the purchase category and the MCC
When a credit card advertises that it offers an additional earn rate for a purchase category (e.g., restaurants), it defines which MCCs are included in the bonus.
For example, when Tangerine talks about Pharmacy to holders of Tangerine credit cards, it refers to merchants classified under 5912 “Pharmacy,” and when it talks about Restaurants, it refers to merchants classified under 5812 to 5814 (“Eating places and Restaurants, Bars, Cocktail lounges, Nightclubs, Taverns and Fast Food Restaurants”).
Reference: https://www.tangerine.ca/en/legal/credit-card-cardholder-agreement (Tangerine money-Back Program Terms and Conditions / Section 7)
The most used codes for the bonus
| Categories | Codes |
|---|---|
| Subscriptions | 7997: Membership Clubs 8699: Membership Organizations |
| Furniture | 5712: Floor Covering Stores 5719: Miscellaneous Home Furnishing Specialty Stores 7641: Furniture, Furniture Repair |
| Bars | 5813: Drinking Places (Alcoholic Beverages), Bars, Tavern |
| Cellular | 4814: Telecommunication Services |
| Airlines | 3000-3299: Brands (Air Canada, Air France, KLM, Lufthansa, ..) |
| Corner Store | 5331: Variety Stores |
| Streaming | 4899: Cable and other pay television |
| Entertainment | 7941: Commercial Sports, Athletic Fields,… 7922: Theatrical Producers (Except Motion Pictures) 7996: Amusement Parks, Carnivals, Circuses 7991: Tourist Attractions and Exhibits 7929: Bands, Orchestras, and Miscellaneous Entertainers 7998: Aquariums, Sea-aquariums, Dolphinariums 7832: Motion Picture Theaters 7829: Motion Pictures and Video Tape Production and Distribution |
| Grocery | 5411: Grocery Stores, Supermarkets 5462: Bakeries 5499: Miscellaneous Food Stores |
| Gas / Refill | 5541: Service Stations (with or without ancillary services) 5542: Automated Fuel Dispensers 5552: Electric Vehicle Charging |
| Hotels-motels | 7011: Hotels and Motels 3500-3828: Brands (Marriott, Sheraton, Hilton, BW, …) |
| Car Hire | 3351-3441: Brands (Hertz, Avis, Alamo, ..) |
| Warehouse stores | 5300: Wholesale Clubs |
| Digital Media | 5815: Digital Goods: Media, Books, Movies, Music 5816: Digital Goods: Games 5968: Direct marketing, continuity subscription merchants |
| Tolls | 4784: Toll and Bridge Fees |
| Drugstores | 5912: Drug Stores and Pharmacies |
| Home Improvement | 5200: Home Supply Warehouse Stores 5231: Glass, Paint, and Wallpaper Stores 5251: Hardware Stores 5261: Nurseries, Lawn and Garden Supply Store 5713: Floor Covering Stores 5714: Drapery, Window Covering and Upholstery Stores 5718: Fireplace, Fireplace Screens, and Accessories Stores |
| Restaurants | 5812: Eating places and Restaurants 5814: Fast Food Restaurants |
| Utilities | 4900: Electric, Gas, Sanitary and Water Utilities |
| Parking | 7523: Automobile Parking Lots and Garages |
| Taxi | 4121: Taxicabs and Limousines |
| Public Transportation | 4111: Local/Suburban Commuter Passenger Transportation 4112: Passenger Railways 4131: Bus Lines, Including Charters, Tour Buses 4789: Transportation Services, Not elsewhere classified |
| SAQ / LCBO | 5921: Liquor Stores |
| Costco / Costco.ca | 5300: Wholesale Clubs |
| Walmart | 5310: Discount Stores or 5311: Department Stores For Mastercard, Supercentres: 5411: Grocery Stores, Supermarkets |
The bonus is therefore calculated at the merchant level, which is why buying a litre of milk in a pharmacy is coded as “Pharmacy,” and buying a toothbrush in a grocery store is coded as “Grocery.”
How to find out the list of MCCs for a purchase type
Knowing how a store is categorized is largely a matter of experience, but there are a few tips.
The cards
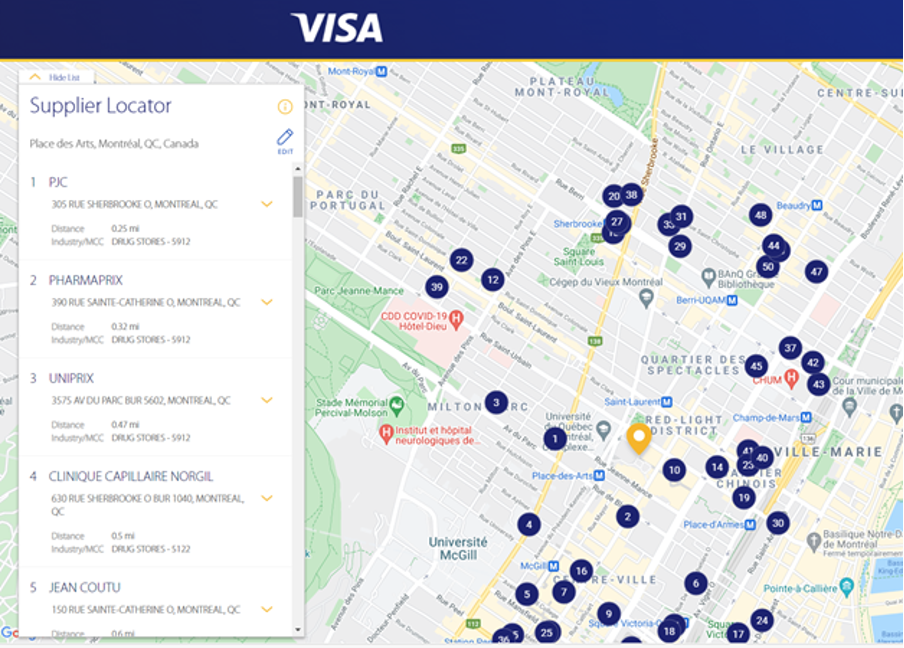
First of all, Visa cards.
Even if these cards only provide the codes for the Visa network, the store is normally coded identically for Mastercard and American Express.
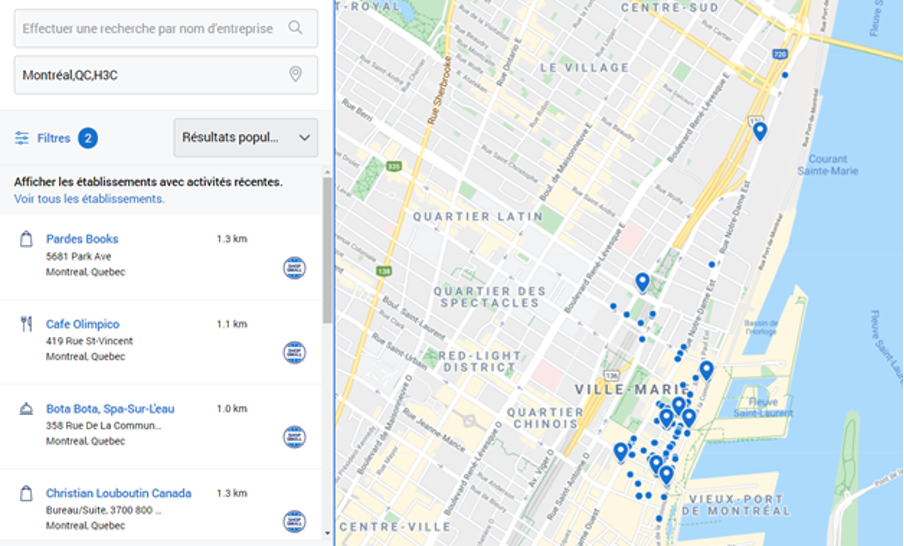
You can also use American Express cards, which are much less precise in categorization but provide a good indication, for example for dining or travel.
Statements
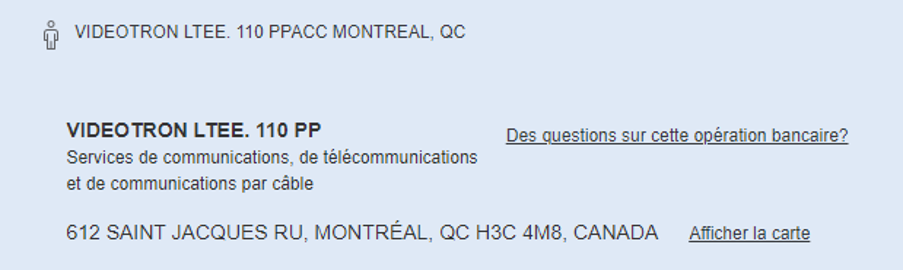
You can also find the classification information on credit card statements when the purchase is posted to the account.
Example with CIBC:
Bottom Line
The calculations are not perfect and are based on the information available from the merchant, card issuer or portal.
Because systems process millions of transaction lines per day, this leads to “errors,” some of which benefit the merchant and others the customer.
Errors that benefit the customer result in losses to the program, but those that benefit the merchant result in dissatisfaction and possibly customer churn, and that is a big risk for the card issuer.
We want to avoid frustrating customers with false positives as much as possible, which is why systems are often more permissive than what is stated in program rules.
It is therefore important to understand the limitations in order to exploit the flaws to one’s advantage.
Join us on the Facebook group to learn more!
- Annual fee
- $0 $139No annual fee the first year
- No annual fee the first year
- Our valuation
- $679Milesopedia first-year estimate First-year valueWelcome bonus$540Annual fee rebated$139Total$679Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Milesopedia first-year estimateFirst-year valueWelcome bonus$540Annual fee rebated$139Total$679Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Welcome offer
- Up to 45,000 points
- + First Year Annual Fee Rebate
on CIBC's website
Our featured card

- Annual fee
- $120
- Our valuation
- $990Milesopedia first-year estimate First-year valueWelcome bonus$990Total$990Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Milesopedia first-year estimateFirst-year valueWelcome bonus$990Total$990Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Welcome offer
- Up to 110,000 points
- Ends Sep 22, 2026
on American Express's website
Apply with confidence — no impact on your credit scoreApply with confidenceCheck whether your application will be approved before you submit it, with no impact on your credit score*When you apply for a personal American Express Credit Card, we will tell you whether you are eligible without affecting your credit score. So you can apply with confidence.*Instant decisions are only available for consumer Card applications (also called “personal Cards”).
Our editorial integrity
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.