Tangerine Rewards World Elite vs Scotiabank Passport Visa Infinite+: Which One Wins?
Loading article…
The Scotiabank Passport® Visa Infinite +* Card becomes, from year two, the more rewarding of the two as soon as you spend about $1,500 a year in foreign currency, because it charges no foreign transaction fees. Below that threshold, the Tangerine® Rewards World Elite Mastercard®* takes the lead thanks to its $30 lower annual fee and its changeable categories. In year one, its 50,000 Scene+ point welcome bonus also puts it ahead on both of our profiles, frequent travellers included.
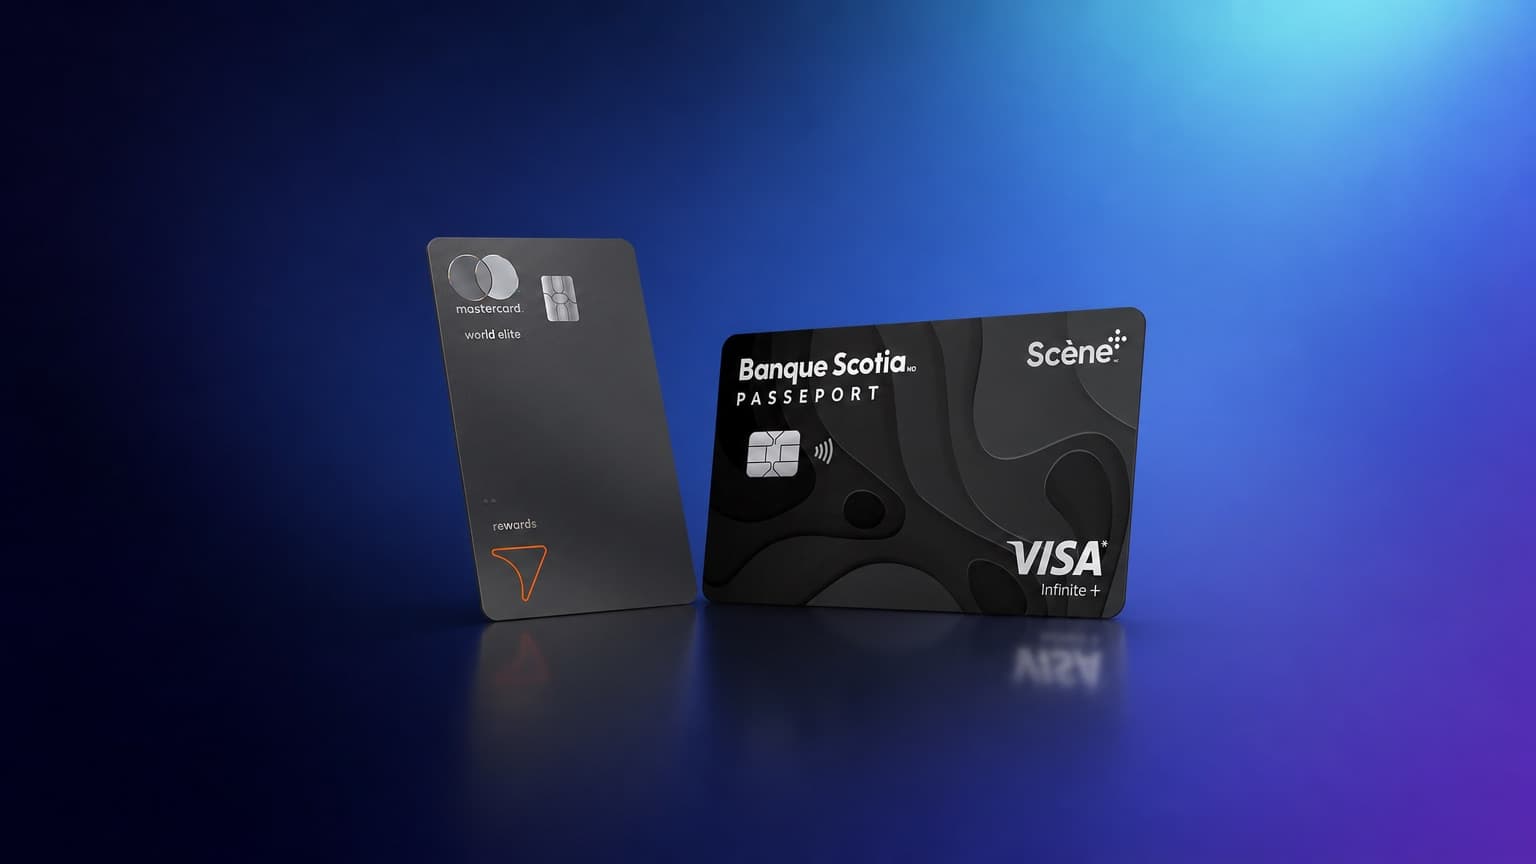
The arrival of the Tangerine Rewards World Elite Mastercard created a situation Canada had not seen before: two cards from different banks now earn the same loyalty currency, $30 apart in annual fees. Below is every point of comparison (fees, eligibility, welcome bonuses, earn rates, benefits and insurance), followed by the net gain worked out on two concrete spending profiles.
Click a card name to see its full profile and current terms.
The Scotiabank Passport Visa Infinite + Card is an unapologetic travel card. Its central argument remains the absence of foreign transaction fees, rounded out by six lounge visits a year and the better emergency medical coverage of the two.
The Tangerine Rewards World Elite Mastercard works differently. It applies Tangerine's house recipe, bonus categories you choose yourself, but transposes it into the Scene+ program rather than into cash back.
Because both cards credit the same Scene+ account, your points pile up in one place. Our guide to maximizing your Scene+ points covers the best redemption routes, in groceries as much as in travel.
| Criterion | Scotiabank Passport Visa Infinite +* Card | Tangerine Rewards World Elite Mastercard |
|---|---|---|
| Annual fee | $150 | $120 |
| Additional cards | 1st at $0, then $50 | $30 per card, from the first |
| Income required | From $60,000 personal or $100,000 household | $80,000 personal or $150,000 household |
| Welcome bonus | 25,000 Scene+ points, or $250 ($2,000 in purchases in 3 months, account opened by November 1, 2026) | 50,000 Scene+ points, or $500 ($5,000 in purchases in 3 months, apply by January 31, 2027) |
| Recurring annual bonus | 10,000 points at $40,000 in purchases, then 2,000 points per additional $10,000 | 10,000 points at $30,000 in purchases |
| Best rate | 3 points per dollar at affiliated grocers | 1.5 points per dollar in 3 chosen categories |
| Foreign transaction fees | 0% | 2.5% |
| Lounge access | 6 per year | 4 per year |
| Medical coverage at 65 and over | 3 days | None |
| Accepted at Costco | Not in warehouses (yes on costco.ca) | Yes |
On sticker price, Tangerine wins: $120 against $150, and $30 per additional card against $50. Note, however, that Scotiabank's first additional card is free, while Tangerine charges $30 from the first one. Neither waives the first year's fee: you pay the full amount from the day you open the account.
The real filter, however, sits in the eligibility terms, and that is where the ranking flips. Scotiabank asks for at least $60,000 in personal income or $100,000 for the household, while Tangerine requires $80,000 or $150,000, the standard thresholds of a World Elite Mastercard.
Put plainly, a reader earning $65,000 a year qualifies for the Scotiabank card but not the Tangerine one. Our guide to credit card eligibility criteria explains how to aim for the right tier the first time.
Both issuers accept proof of assets in place of income. Tangerine mentions $400,000 in assets under management, and Scotiabank shows a $250,000 to $300,000 range on its official page. This entry point serves the self-employed and retirees whose declared income is low despite solid holdings.
Before you apply, make sure your income meets the stated threshold and that your credit file is in good order: every application leaves a hard inquiry on your file. If you are looking for another travel card with solid insurance, the National Bank World Elite Mastercard keeps 15 days of medical coverage even after 65.
on National Bank's website
Scotiabank imposes its categories, Tangerine lets you choose them. That single design difference explains most of the performance gap from one profile to the next.
| Spending category | Scotiabank Passport Visa Infinite +* Card | Tangerine Rewards World Elite Mastercard |
|---|---|---|
| Groceries at Sobeys, IGA, Safeway, Foodland | 3 points per dollar | 1.5 points if groceries is one of your 3 picks |
| Other grocery stores | 2 points per dollar | 1.5 points if groceries is one of your 3 picks |
| Restaurants | 2 points per dollar | 1.5 points if restaurants is one of your 3 picks |
| Entertainment | 2 points per dollar | 1.5 points if entertainment is one of your 3 picks |
| Local public transit | 2 points per dollar | 1.5 points if transit is one of your 3 picks |
| Gas | 1 point per dollar | 1.5 points if gas is one of your 3 picks |
| Recurring bills | 1 point per dollar | 1.5 points if bills is one of your 3 picks |
| All other purchases | 1 point per dollar | 1 point per dollar |
At Tangerine, you keep 3 categories out of the following 13, and you can change them every 90 days depending on the season or a project under way.
In practice, Tangerine's flexibility pays off mostly on the categories Scotiabank ignores: gas, recurring bills, home improvement and drug store all earn just one point per dollar there. Conversely, a household shopping at IGA or Sobeys collects 3 points per dollar with Scotiabank, double Tangerine's best rate.

According to the terms published by Scotiabank, the accelerated categories on the Scotiabank Passport Visa Infinite + Card are capped at $50,000 in purchases per calendar year, from January 1 to December 31. Above that, the rate falls back to 1 point per dollar. This cap stays out of reach for the vast majority of households, but it matters if you concentrate all your family spending on a single card.
A single calculation settles the question. The annual fee gap between the two cards is $30. So the question becomes simple: how much foreign currency spending does it take to offset those $30?
On a foreign currency purchase, the Scotiabank Passport Visa Infinite + Card earns 1 point per dollar, or 1%, and charges nothing. The Tangerine Rewards World Elite Mastercard earns 1.5 points per dollar if you kept foreign currency spending among your 3 categories, or 1.5%, but it charges 2.5% in foreign transaction fees. The net return falls to minus 1%.
The real gap therefore reaches 2 percentage points in Scotiabank's favour. It takes only $1,500 in annual foreign currency spending to cancel out the extra $30 in annual fees, roughly two weeks down south for a couple.
| $1,500 in foreign currency purchases | Scotiabank Passport Visa Infinite +* Card | Tangerine Rewards World Elite Mastercard |
|---|---|---|
| Points earned | 1,500 points, or $15 | 2,250 points, or $22.50 |
| Foreign transaction fees paid | $0 | $37.50 |
| Net result | $15 | −$15 |
Note that this threshold drops to $1,200 if you did not keep foreign currency spending among your 3 Tangerine categories, which will be the case for most cardholders. To go further on this point, compare the best credit cards with no foreign transaction fees.
Take a first profile: $600 of groceries a month including $400 at IGA, $300 of restaurants, $100 of entertainment, $80 of local transit, $150 of gas, $250 of recurring bills, $700 of foreign currency purchases and $400 of other purchases. Total of $2,580 a month, or $30,960 a year.
On the Tangerine side, this reader keeps groceries, restaurants and foreign currency spending as bonus categories, the most favourable choice available.
| Traveller profile, $30,960 a year | Scotiabank Passport Visa Infinite +* Card | Tangerine Rewards World Elite Mastercard |
|---|---|---|
| Points earned in year 1 | 48,720 Scene+ points | 40,560 Scene+ points |
| Value of earnings | $487 | $406 |
| Welcome bonus | $250 | $500 |
| Recurring annual bonus | $0 ($40,000 threshold not met) | $100 ($30,000 threshold met) |
| Foreign transaction fees on $8,400 | $0 | −$210 |
| Annual fee | −$150 | −$120 |
| Net gain, year 1 | $587 | $676 |
| Net gain, year 2 | $337 | $176 |
In year one, Tangerine comes out $89 ahead, a gap that hides four opposing movements. Scotiabank gains $210 in avoided foreign transaction fees and $81 in extra earnings thanks to the 3 points per dollar at affiliated grocers. On the other hand, it gives up $250 on the welcome bonus, $100 on the out-of-reach annual bonus and $30 in extra annual fees.
In year two, Scotiabank takes a clear lead, $161 ahead, since the welcome bonuses drop out on both sides and only the foreign transaction fees keep running.
These figures deliberately exclude the value of lounge access, which is hard to monetize on a comparable basis. Tangerine values its 4 annual passes at $291, but that value only counts if you actually use them.
Change readers. This family shops at Costco and Maxi, never sets foot in a Sobeys banner, is renovating its kitchen and makes no foreign currency purchases. Its monthly budget: $900 of groceries including $300 at Costco, $200 of restaurants, $200 of gas, $100 of drug store, $300 of recurring bills, $200 of home improvement and $400 of other purchases. Total of $2,300 a month, or $27,600 a year.
Here, a hard constraint comes into play. In its Canadian warehouses, Costco accepts only Mastercard network cards, which rules out the Scotiabank Passport Visa Infinite + Card (it is still accepted on costco.ca). The $300 of monthly Costco groceries must therefore go on another card, and they earn nothing in this calculation. At Tangerine, they earn 1 point per dollar, because wholesale clubs are excluded from the grocery category.
| Household profile, $27,600 a year | Scotiabank Passport Visa Infinite +* Card | Tangerine Rewards World Elite Mastercard |
|---|---|---|
| Spending charged to the card | $24,000 (Costco excluded) | $27,600 |
| Points earned in year 1 | 33,600 Scene+ points | 34,200 Scene+ points |
| Value of earnings | $336 | $342 |
| Welcome bonus | $250 | $500 |
| Recurring annual bonus | $0 | $0 ($30,000 threshold not met) |
| Annual fee | −$150 | −$120 |
| Net gain, year 1 | $436 | $722 |
| Net gain, year 2 | $186 | $222 |
For this household, Tangerine comes out $286 ahead in year one, then $36 ahead in year two. Four elements explain the gap: its more generous welcome bonus, Costco access, the 1.5 points on gas and recurring bills that Scotiabank does not accelerate, and the $30 lower annual fee.
One nuance matters, though. If that same family did its groceries at IGA rather than at Maxi and Costco, Scotiabank would recover roughly $180 a year in extra points. Tangerine would stay ahead in year one thanks to its welcome bonus ($740 against $616), but Scotiabank would retake the lead from year two ($366 against $240). Your grocery banner therefore counts as much as your budget, a point our guide to credit card spending categories develops in detail.
On benefits beyond points, each card defends different ground. Scotiabank bets on the airport, Tangerine on daily life and the gas station.
The Scotiabank Passport Visa Infinite + Card gives 6 lounge visits a year through the Visa Airport Companion program, against 4 DragonPass visits at Tangerine, billed US$32 per visit beyond that. It adds the Visa Infinite Concierge, the Visa Infinite Hotel Collection and the Visa Destinations program.
On the Tangerine side, two benefits stand out. The Shell partnership gives up to 10¢ per litre in combined value, and FlexiRoam provides 3 GB of international roaming data a year, at no extra cost.
If lounges weigh heavily in your decision, start by comparing the best credit cards for airport VIP lounges, because four or six visits go quickly on a family trip.
Before 65, you are covered for the essentials of a trip with either card. After that age, medical coverage shrinks on both, and this criterion alone can decide your choice.
At Tangerine, emergency medical insurance covers the first 15 days of a trip, only for travellers under 65. At 65, medical coverage disappears entirely.
At Scotiabank, the duration reaches 25 days up to age 64, then drops to 3 days from 65. The coverage survives, but 3 days is not enough for any real trip.
| Protection | Scotiabank Passport Visa Infinite +* Card | Tangerine Rewards World Elite Mastercard |
|---|---|---|
| Emergency medical, under 65 | $2,000,000 for 25 days | Up to $5,000,000 for 15 days |
| Emergency medical, 65 and over | $2,000,000 for 3 days | No coverage |
| Trip cancellation | $1,500 per person | Up to $2,000 per person |
| Trip interruption | $2,500 per person | Up to $2,000 per person |
| Flight delay | $500 | $500 per trip (delay of 4 hours or more) |
| Lost or stolen baggage | $1,000 | $1,000 per person per trip |
| Rental car | $65,000 for 48 days | Included, up to 48 days of rental |
| Mobile devices | Not included | Up to $1,500 |
| Purchase protection | 90 days | 90 days, $60,000 lifetime maximum |
Durations, amounts and age brackets change from one insurance certificate to another, and insurers revise them regularly. Read the certificate that came with your card before each trip, and plan for supplementary insurance as soon as the length of your stay exceeds the covered period. We lay out the steps in our guide to extending the travel insurance on the Scotiabank Passport Visa Infinite Card.
For a reader aged 65 and over, our position is clear: neither one. Our best credit cards for travel insurance present options that keep 15 days of coverage past that age.
One option exists on the Scotiabank side with no equivalent at Tangerine: the annual fee rebate tied to a banking package. This detail completely changes the result of the two tables above.
According to the terms published by Scotiabank, the Ultimate Package refunds all $150 of the annual fee, and the Preferred Package refunds $40 provided you charged $15,000 in eligible purchases to the account over the 12 statement periods before the fee is billed. The first annual fee billed after June 22, 2026 does not qualify for this $40 rebate, though.
So a reader who already banks with Scotiabank and holds the Ultimate Package pays $0 for the card. On our household profile, that would take the net gain from $436 to $586 in year one, still behind Tangerine ($722), then from $186 to $336 in year two, this time ahead of Tangerine ($222). Our analysis of the Ultimate Package paired with the Scotiabank Passport Visa Infinite Card puts numbers on that setup in detail.
That said, the package's monthly fees have to enter your calculation too. The rebate only makes sense if you would have opened that account anyway.
Each card wins on its own ground, and your profile decides. The right choice depends on four variables: your volume of foreign currency spending, your grocery banner, your income, and your current banking relationship.
| Your situation | Our recommendation |
|---|---|
| More than $1,500 a year in foreign currency | Scotiabank Passport Visa Infinite +* Card |
| Groceries at Sobeys, IGA, Safeway or Foodland | Scotiabank Passport Visa Infinite +* Card |
| Income between $60,000 and $79,999 | Scotiabank Passport Visa Infinite +* Card, the only one of the two available |
| Ultimate Package already held at Scotiabank | Scotiabank Passport Visa Infinite +* Card |
| Groceries at Costco, Maxi, Metro or Loblaws | Tangerine Rewards World Elite Mastercard |
| Large gas or recurring bill budget | Tangerine Rewards World Elite Mastercard |
| Renovations or furniture purchases planned | Tangerine Rewards World Elite Mastercard |
| No trips abroad planned | Tangerine Rewards World Elite Mastercard |
| 65 and over, medical coverage required | Neither, see our cards for travel insurance |
For a reader who clears both income thresholds, the combination holds up, and it has a rare merit: the points land in the same Scene+ account, with no scattering across two programs.
The method is simple. The Scotiabank card comes out of the wallet for anything in foreign currency and for Sobeys-affiliated groceries. The Tangerine one takes over for gas, recurring bills, home improvement and Costco.
The combined cost comes to $270 a year, or only $120 if your Ultimate Package refunds the Scotiabank fee. On the other hand, each card's 10,000-point annual bonus becomes harder to earn, since your spending splits across two statements instead of one.
Be careful not to stack applications either. Two account openings close together leave two hard inquiries on your credit file, and we recommend spacing applications at least 90 days apart.
To access member-only offers, save your favourite cards and choose which newsletters you receive, create your free member account.
To go further:
on Tangerine's website
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.