How to Quickly Eliminate Your Credit Card Debt in 2026
Discover how to quickly eliminate your credit card debt in Canada in 2026. Practical strategies to repay your balances and avoid new debts.
Are you concerned about your credit card debt and don’t know where to start repaying it? You are not alone. Credit card debt accumulates quickly with high interest and can become a real financial burden.
In this article, you will discover what credit card debt is, why it can pose a danger to your finances, and how to plan your payments to eliminate it effectively. We will also look at strategies to avoid new debts and when to consider consolidation or professional help. These practical tips will help you regain control of your budget and achieve financial peace of mind, step by step.
What is credit card debt?
Credit card debt arises when you use your card without repaying the full balance each month. Interest quickly adds up, increasing the total amount due.
Each card has an annual rate, which can vary considerably. Even small balances can grow quickly if only minimum payments are made. Understanding your credit card debt is the first step to developing an effective repayment plan and preventing your situation from becoming unmanageable.
Why Credit Card Debt is Dangerous
Credit card debt can harm your financial health and your credit score. A high balance incurs significant interest charges, limiting your ability to save or invest.
Furthermore, a late payment can affect your credit file, making it difficult to obtain loans or favorable rates in the future. Understanding these risks helps you prioritize repayment and adopt effective strategies to reduce your debts quickly.
10 Strategies to Eliminate Your Credit Card Debt
1. Pay off high-interest debts first (Avalanche method)
Cards with high rates cost more each month. By paying these off first, you quickly reduce the total amount paid in interest. This strategy allows you to save in the long term and free up more money to pay off other debts. To find out more, consult the following guide:
2. Pay off the smallest debts first (Snowball method)
This approach involves paying off cards with the smallest balances first. Each debt settled provides psychological motivation and a sense of accomplishment, which encourages you to continue your repayment plan.
3. Pay more than the minimum each month
Paying only the minimum prolongs repayment and increases interest charges. Even a small additional amount significantly reduces your balance over the months and can improve your utilization rate, which is beneficial for your credit score.
4. Transfer the balance to a low-interest card
A balance transfer allows you to move the balance from your high-interest cards to a new card offering a very low promotional rate or even 0% for several months. This gives you a break from interest, helping you focus your payments on repaying the principal rather than fees.
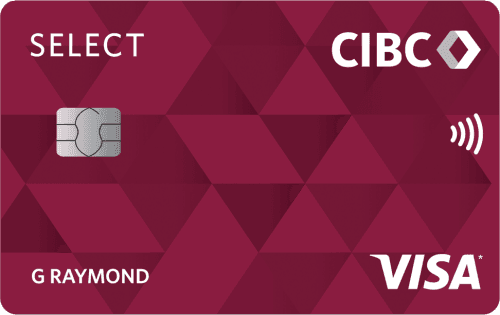
One popular card for balance transfers is the CIBC Select Visa* Card, which offers 0% for 10 months on transfers of $100 or more, with a 1% transfer fee.
Other options may offer a low or near-zero promotional rate for a limited period, depending on promotions.
- Annual feeNo annual fee the first year
- $0 $29
- First year free
- Our valuationMilesopedia first-year estimate First-year valueAnnual fee rebated$29Total$29Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- $29
- Welcome offer$29 annual fee rebated
- First-Year Annual Fee Rebate
on CIBC's website
How it works:
- Compare offers: check the duration of the promotional period, transfer fees (often 1% to 3% of the amount), and the rates that apply after the promotion.
- Apply for the new card: apply online and, once approved, initiate the transfer with the old issuer.
- Plan your payments: calculate how much you need to repay during the low-rate period to avoid higher interest rates applying later.
For a complete explanation of how balance transfers work, consult our following guides:
5. Establish a clear and realistic budget
A budget allows you to know exactly how much you can allocate to repayment each month. List your income, fixed expenses, and debts, then set specific goals to gradually repay your cards.
6. Limit your credit card usage
The more you use your cards without quick repayment, the more your debt increases. A good practice is to only use the card if the money is already available, which helps you avoid accumulating new debts.
You can also consider a debit card or a prepaid card to better control your spending. For example, the KOHO Prepaid MastercardMD or the Neo Money Card allows you to easily manage your budget and limit your expenses, while facilitating the repayment of accumulated credit card debt.
7. Negotiate a Lower Interest Rate
There is no harm in contacting your credit card provider to request a reduction in your interest rate. Mention how many years you have been a customer and your punctual payment habits. A rate reduction accelerates the repayment of your debts.
If no negotiation is possible, consider applying for a low-interest credit card, which can also help you reduce your fees and repay faster.
8. Automate Your Payments
Scheduling your monthly payments avoids delays and additional fees. Automation ensures your debts are repaid regularly and can help improve your credit score.
9. Consider a Lower-Interest Personal Loan
A personal loan at a lower rate than your cards can consolidate your debts and reduce interest paid. Always compare the total cost before choosing this option to ensure it is advantageous.
10. Explore Debt Consolidation if Appropriate
Consolidation groups several debts into a single payment with a potentially lower rate. This method simplifies management and can reduce your fees. However, it is not suitable for everyone and requires careful analysis.
Line of Credit or Fixed Payments?
According to the Financial Consumer Agency of Canada (FCAC), a personal line of credit usually carries a variable interest rate that is lower than a credit card's. However, its minimum payment generally covers only that month's interest. Moving the debt to a line of credit is therefore not enough on its own: the fixed amount you pay each month is what decides when the debt is gone.
Here is a simplified estimate for a $15,500 balance, with no new purchases and interest calculated monthly:
- Card at 19.99%, $400 a month: about 63 months and $9,600 in interest
- Card at 19.99%, $1,000 a month: about 19 months and $2,600 in interest
- Line of credit at 9%, $400 a month: about 46 months and $2,900 in interest
- Line of credit at 9%, $1,000 a month: about 17 months and $1,000 in interest
The payment amount matters more than the rate. On the card, going from $400 to $1,000 a month saves about $7,000 in interest, while a 9% line of credit at the same $400 payment saves about $6,700. Combining both gives the best result. The 9% rate is only an example: your actual rate depends on your credit score and income. Also, a variable-rate line of credit follows the lender's prime rate, which stood at 4.45% at RBC as of September 25, 2026. Finally, stop using the card you paid off or keep it at a zero balance; otherwise, you could end up with two debts instead of one.
Improve Your Credit Score
Managing your credit card debt directly influences your credit score. A strong score facilitates access to better interest rates for a mortgage, a car loan, or a line of credit.
Here are some concrete actions:
- Pay your bills on time: punctuality accounts for approximately 35% of your credit score.
- Reduce your credit utilization rate (ideally, less than 30%).
- Keep old credit lines open to build a strong history.
- Avoid new credit applications just before a major project (e.g., a mortgage).
- Diversify your credit types (cards, personal loan, line of credit).
KOHO‘s credit improvement option, called “KOHO Credit Building”, allows you to build a credit history safely and controllably.
For more details, consult our complete guide on how to improve your credit score.
Planning and Avoiding New Debts
To avoid falling back into credit card debt, establish a realistic budget and pay your balances in full each month. Limit the number of cards or adjust your limits to better control your spending. Monitor your transactions regularly to identify habits to correct and stay on the path to financial health.
These same habits also help you keep other costs in check: see our guide on how to avoid credit card fees in Canada to spot every avoidable charge.
When to Consider Consolidation or Professional Help
If your credit card debt accumulates despite your efforts, consolidation or a financial advisor can be helpful. Compare options like personal loans or balance transfers before choosing. A professional can negotiate with your creditors and create a plan tailored to your situation to quickly get out of the debt spiral.
Bottom Line
Eliminating your credit card debt requires discipline, but understanding credit card debt and its impacts is the first step. By applying the strategies explained in this article, you can reduce your balances, protect your credit file, and prevent new debts from accumulating.
Planning your payments, using methods adapted to your situation, and, if necessary, considering consolidation or professional help are concrete solutions to regain control. To go further, explore our article on improving your credit score. Act today and free yourself from your credit card debt.
What are the main causes of credit card debt?
Credit card debt often stems from unplanned expenses, unpaid balances, or high interest rates.
Which repayment strategy should you choose?
The Snowball method targets small debts, and the Avalanche method, high-interest debts. Choose according to your situation and motivation.
Can I consolidate my debts?
Yes. Consolidation can reduce interest and simplify payments via a personal loan or a balance transfer.
Will a debt consolidation loan hurt my credit score?
Not necessarily. According to the Financial Consumer Agency of Canada (FCAC), debt consolidation can help your credit score if you make your payments on time and reduce the number of accounts with high balances. However, applying for loans with several lenders in a short period can lower your score. Also make sure the loan's rate is lower than the rate on your current debts: otherwise, consolidation will cost you more.
Consolidation loan or balance transfer: which should you choose?
A consolidation loan comes with regular payments, at a fixed or variable rate, until an end date. A balance transfer instead offers a reduced promotional rate, sometimes 0%, for a limited time that usually ranges from 6 to 18 months according to the FCAC (checked on October 26, 2026). Transfer fees, usually a percentage of the amount transferred, apply, and you can lose the promotional rate if you miss a payment.
How to avoid new debts?
Pay the full balance, plan your purchases, and follow a realistic budget. Limiting your cards can also help.
When to consult an advisor?
If your debts accumulate despite your efforts, an advisor can help you develop a tailored plan and negotiate with your creditors.