

Wealthsimple Kids and Teens Account: Prepaid Visa Card and Up to 2.25% Interest
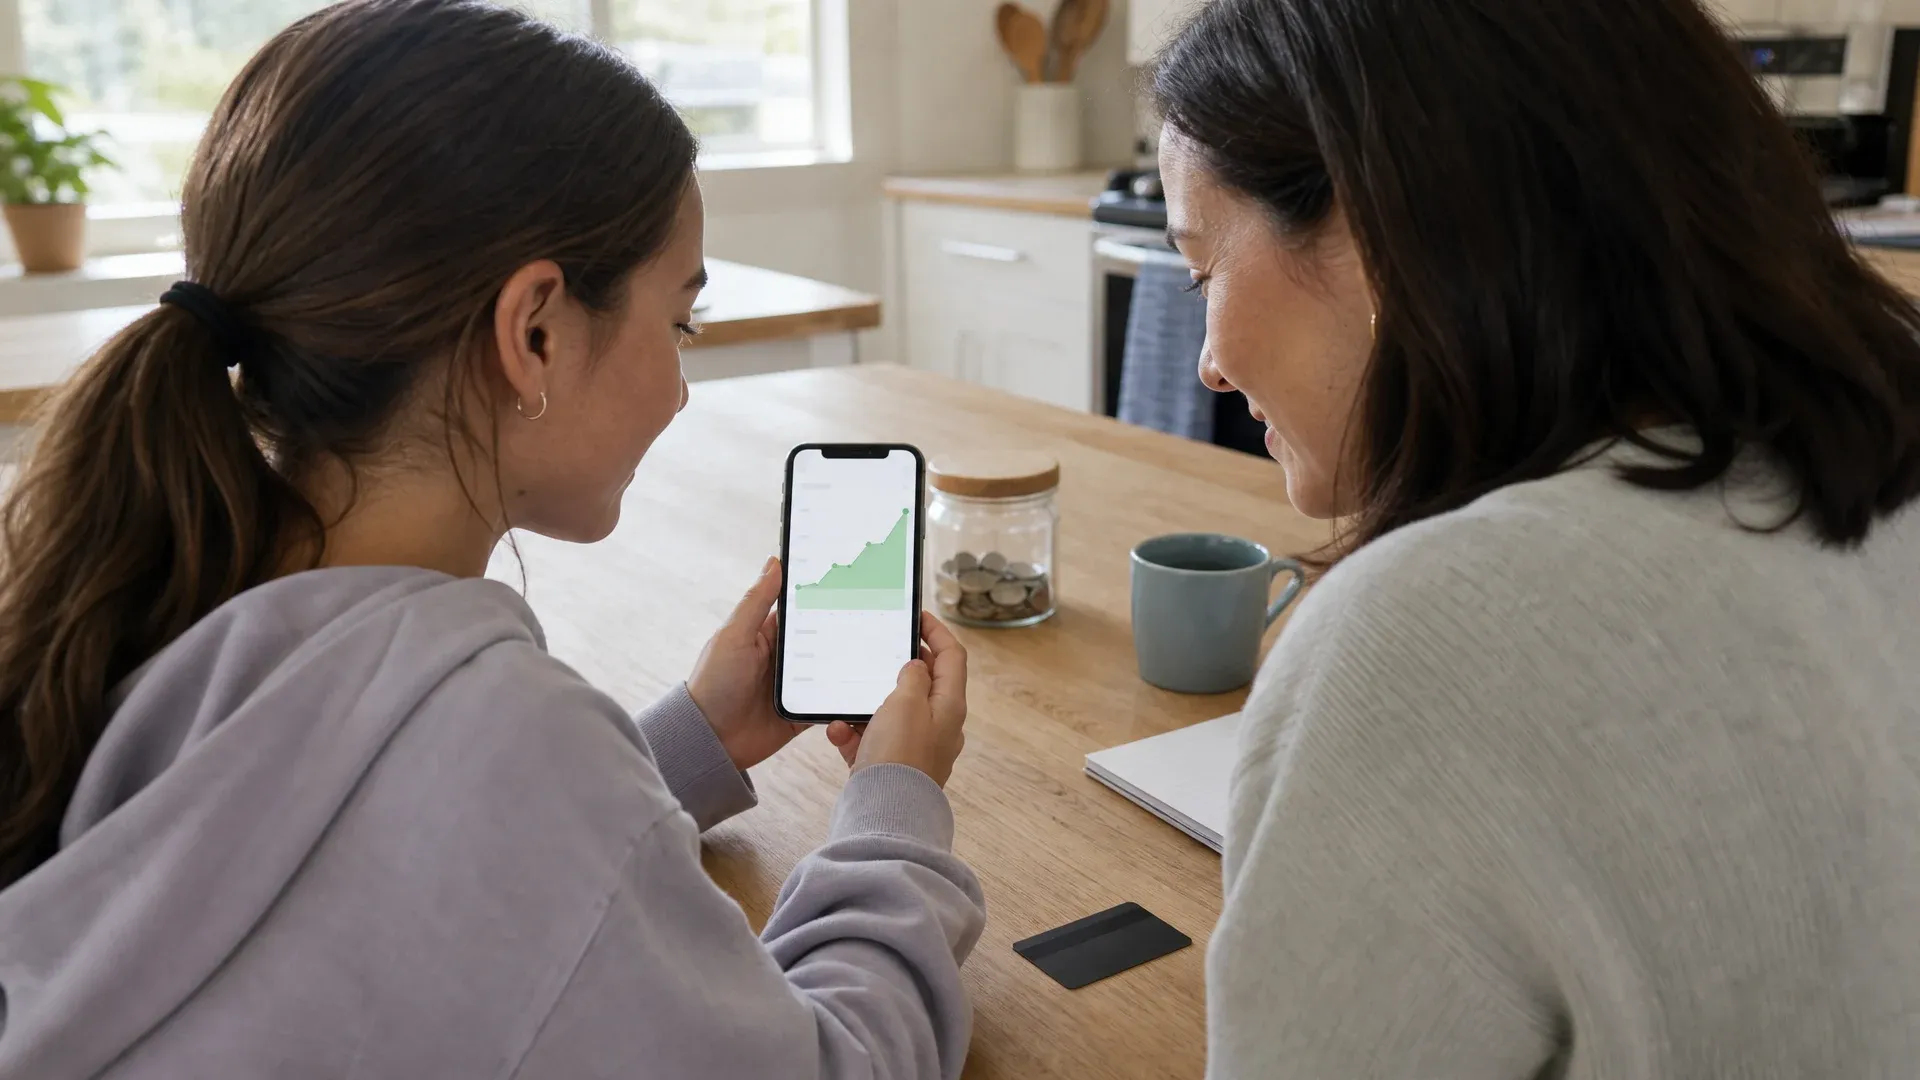
The Wealthsimple kids account, built for kids and teens, is now available in Canada, as Wealthsimple announced on its official page. It gives your child a prepaid Visa card, an interest rate of up to 2.25%, scheduled allowances and parental controls, all with no monthly fees. There is one catch for Quebec families: as of September 2026, the account is not available in Quebec yet.
First announced in May as part of Wealthsimple Family, the product is now open to Wealthsimple parents elsewhere in the country. Wealthsimple also says Interac® e-Transfers and direct deposit are coming soon. Here is how it works, what it costs and where it falls short.
Wealthsimple kids and teens account at a glance
It is a chequing account that a parent opens and manages on behalf of their child. Legally, it is a bare trust: you are the legal account holder and trustee, and your child is the beneficial owner of the funds. Statements and T5 slips are issued as "[your name] in trust for [child's name]".
Your child gets a Kids and Teens prepaid Visa card and a simplified version of the app. You keep control of spending limits, blocked categories and notifications.
Who can open a Wealthsimple kids account?
To open a kids and teens account, you must meet three conditions:
- be an existing Wealthsimple client with an open chequing account;
- have completed identity verification;
- open the account for a child under the age of majority in their province (18 or 19, depending on the province).
You can link up to 10 kids and teens accounts to your profile. Your child does not need to provide ID. Accounts are opened only in the mobile app, and it takes a few minutes.
The prepaid Visa card for kids
As soon as the account is open, Wealthsimple issues a virtual card that works with Apple Pay or Google Pay. The physical card is optional and arrives by mail. It can be used to withdraw cash at ATMs.
The card also carries two perks from the adult Wealthsimple chequing account: no foreign exchange fees and ATM fee reimbursements worldwide. However, it earns no cash back.
| Feature | Details |
|---|---|
| Monthly fees | None |
| Minimum balance | None |
| Interest rate | Same as the parent's chequing account: 1.25%, 1.75% or 2.25% |
| Card | Prepaid Visa, virtual at opening, physical card optional |
| Foreign exchange fees | None |
| ATM fees | Reimbursed worldwide |
| Cash back | None |
| Limit per transaction | $999 (deposit, allowance, withdrawal, purchase) |
| Tap limit (physical card) | $250 |
| Age | Up to the age of majority (18 or 19, depending on the province) |
| Quebec | Not available for now |
Up to 2.25% interest, with conditions
The 2.25% figure Wealthsimple promotes is a maximum. Your child's account earns the same rate as the parent's chequing account, and that rate depends on your client status:
- 1.25% for all clients with a chequing account;
- 1.75% for Premium clients, or Core clients with an eligible direct deposit;
- 2.25% for Generation clients, or Premium clients with an eligible direct deposit.
In other words, most families will earn 1.25% or 1.75%. To understand these tiers, read our article on Wealthsimple Premium and Generation accounts.
Parent-paid interest
This is the most original feature of the product. With parent-paid interest, you top up the rate your child earns yourself. A slider lets you pick a combined rate from 10% to 100%, and the app shows a projection of the balance over time.
Each month, Wealthsimple calculates the amount and moves it from your account to your child's on the 1st. It is not real interest: it is a payment from you, presented as interest to make saving feel concrete. If your account does not have enough money on the 1st, that month's payment is skipped. After two failed payments in a row, the feature turns off.
Allowances and transfers
You can send a one-time transfer or schedule a weekly, bi-weekly or monthly allowance. The money arrives instantly. Your child can also send you a money request, which you approve or decline.
There is one important constraint: for now, only your own Wealthsimple chequing account can fund the account. Each transaction is capped at $999, whether it is a deposit, an allowance payment or a withdrawal. Interac e-Transfers, direct deposit and higher limits are listed as "coming soon", with no date.
Parental controls
From your own app, you can:
- set spending limits per transaction, per day, per week or per month;
- block in-person purchases, online purchases or ATM withdrawals;
- turn off international purchases;
- block certain categories, starting with digital gaming and in-app purchases;
- get a real-time notification for every purchase;
- lock the card. If your child locks it, only you can unlock it.
You can also invite a co-manager, who does not have to be the other parent. A co-manager can set limits and lock the card. However, they cannot order the card, set up parent-paid interest or close the account.
What to know before opening an account
First, the money belongs to your child. You can take it out to pay for something for your child, but using it for yourself breaches your duties as trustee.
Second, taxes need some attention. If the money comes from you, attribution rules generally mean you report the interest. Wealthsimple also notes that a T3 return may be required and recommends speaking with a tax professional.
In addition, the account is not eligible for Wealthsimple promotions, referral programs or bonuses. Finally, it is not an education savings tool. An RESP is still the right account for that, and Wealthsimple now offers the QESI in its RESP in Quebec.
What about Quebec?
Wealthsimple says the account is not available in Quebec "due to legal and regulatory differences in the province". The company says it is working on bringing it to Quebec, with no date announced. If you open an account elsewhere in Canada and then move to Quebec, the account stays open, but you cannot open a new one.
In the meantime, Quebec parents have other options. Several credit cards let you add a teenager as an additional cardholder; our article on the minimum age for an additional credit card covers the details. For the basics, see our tips on introducing your children to personal finance.
The Milesopedia angle for families
Teens who travel with no FX fees
For families who travel on points, the kids card has one concrete advantage: no foreign exchange fees and ATM fee reimbursements worldwide. Your teen can pay for meals or withdraw cash on a family trip, a school trip or a student exchange without the roughly 2.5% FX fee most Canadian cards charge.
You also keep control from a distance: a daily limit, international purchases switched on only for the trip, and a notification for every purchase. To plan your next trip, see our points strategies for family travel during school breaks and this student exchange in Asia paid for with points.
For parents: the Wealthsimple Visa Infinite+ card
The kids account requires a Wealthsimple chequing account in the parent's name. If you already have one, the Wealthsimple Visa Infinite+ Card rounds out the family setup: 2% cash back on every purchase, with no categories, and no foreign exchange fees on your own spending abroad.
- Fees: $20 a month, or $240 a year, waived for Premium and Generation clients or with an eligible payroll direct deposit. Those are the same statuses that give your child's account the best rate.
- Welcome offer: up to $500 cash back, which is 5% on your first $10,000 in purchases during the 30 days after approval.
- Eligibility: a personal income of $80,000 or a household income of $150,000.
At 18: the first credit card
The account stays with your child after they reach the age of majority. It is also the right time to start building a credit history, which will matter for a first apartment or the travel cards they will want one day.
Our guide to the best first credit card for young adults 18 and over and our tips on building a good credit score as a student will help you plan the next step. To compare other bank accounts for young people, see our list of the best chequing accounts.
Our take
For a family already banking with Wealthsimple outside Quebec, this account is a good learning tool. It costs nothing, the card has no foreign exchange fees and the parental controls are thorough. Parent-paid interest is a smart teaching idea, as long as you remember that you are the one paying.
- No fees: no monthly fees, no ATM fees, no minimum balance
- Prepaid Visa card: virtual at account opening, physical card optional, no foreign exchange fees
- Thorough parental controls: spending limits, blocked categories, real-time notifications
- Parent-paid interest: a concrete way to show how saving adds up
- Automatic allowance: weekly, bi-weekly or monthly
However, two limits weigh on it for now. The account can only be funded from your Wealthsimple chequing account, so a grandparent cannot send an Interac e-Transfer for a birthday. And the 2.25% rate only applies to Generation clients or Premium clients with direct deposit.
- Not available in Quebec yet: no date announced
- Limited funding: only from the parent's or co-manager's Wealthsimple chequing account, for now
- $999 cap per transaction: deposit, allowance or withdrawal
- 2.25% rate with conditions: reserved for Generation clients or Premium clients with direct deposit
- No cash back on the card, and no promotions or referral bonuses
If you do not have an account yet, start with our review of the Wealthsimple chequing account, which you need before opening a kids account. And for parents who would rather earn points on family spending, our guide to the best credit cards compares the options.
To get our analysis of new banking products and the best offers every week, subscribe to our newsletter.
Wealthsimple kids and teens account: frequently asked questions
Is the Wealthsimple kids account free?
Yes. The kids and teens account has no monthly fees, no ATM fees and no minimum balance. The prepaid Visa card has no foreign exchange fees. You do need a Wealthsimple chequing account, which also has no monthly fees, to open and fund your child's account.
What interest rate does my child's account earn?
It earns the same rate as your Wealthsimple chequing account, which depends on your client status and direct deposits. As of September 2026, the top rate of 2.25% is reserved for Generation clients and Premium clients with an eligible direct deposit. Other clients earn a lower rate. You can then add parent-paid interest on top.
Is the Wealthsimple kids and teens account available in Quebec?
Not yet. Wealthsimple cites legal and regulatory differences in Quebec and says it is working on making the account available there, with no set date. An account opened elsewhere in Canada stays open if the family moves to Quebec, but you cannot open a new one for a child who lives there.
How old does my child need to be?
Wealthsimple does not set a minimum age. The account is available to any child under the age of majority in their province, which is 18 or 19. When your child reaches the age of majority, nothing changes right away: they can keep using their account and card. To pick the right time, our tips on introducing your children to personal finance can help.
How does parent-paid interest work?
You pick a combined rate from 10% to 100% with a slider in the app. On the 1st of each month, Wealthsimple calculates your share based on your child's balance and moves it from your account to theirs. This amount is not interest paid by Wealthsimple: it is a payment from you, presented as interest to show how saving adds up.
Who pays tax on the interest in my child's account?
In most cases, if the money comes from a parent or grandparent, attribution rules mean the adult reports the interest. If the account holds the child's own money, such as a salary or the Canada Child Benefit, the child generally reports it. Wealthsimple recommends speaking with a tax professional, since a T3 return may be required.
When will Interac e-Transfers be available?
Wealthsimple says Interac e-Transfers, direct deposit and higher transfer and spending limits are coming soon, with no set date. For now, only the Wealthsimple chequing account of the parent or co-manager can fund the account, up to $999 per transaction.
Our featured card

- Annual fee
- $240
- Our valuationMilesopedia first-year estimate First-year valueWelcome bonus$500Total$500Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- $500
- Welcome offerAfter $10,000 in 1 month
- Up to $500 cash back
on Wealthsimple's website
Our editorial integrity
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.