

Rogers Mastercard Cards: Annual Spending Caps on Accelerated Cash Back Rates Starting August 2026
Starting August 4, 2026, Rogers Bank applies annual cash back caps to three of its four Red Mastercard cards. Spending thresholds range from $16,000 to $61,000; past the cap, the accelerated rate drops to the base rate. The World Legend card stays uncapped.
Rogers Bank has announced significant changes for its Rogers Red Mastercard cards. Starting August 4, 2026, three of the four cards in the Rogers portfolio will be subject to annual caps on accelerated cash back accumulation. Only the Rogers World Legend Mastercard is exempt. Meanwhile, the interest rate on purchases is increasing from 20.99% to 21.99% across all cards.
These changes particularly affect Rogers, Fido, Shaw, and Comwave customers who have enjoyed 2% cash back without restrictions until now. Here’s what’s changing, card by card.
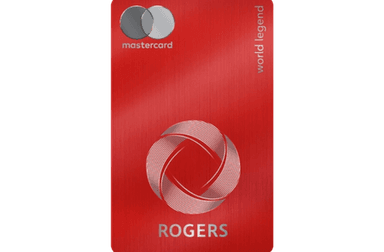
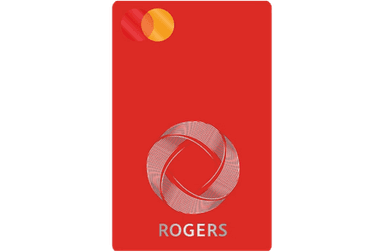
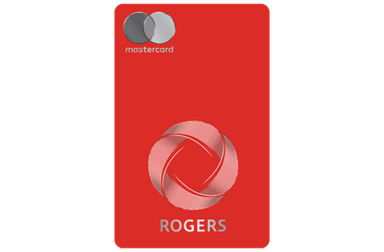
| Credit card | Annual fee | Welcome offer | |
|---|---|---|---|
| $495 | |||
| $0 | |||
| $0 |
What Changes on August 4, 2026
Rogers Bank is introducing two distinct modifications. First, the interest rate on purchases will increase from 20.99% to 21.99% on all four Red Mastercard cards. This change aligns Rogers with the majority of Canadian issuers. Second, annual earnings caps will apply to the accelerated cash back rate of three cards.
Note: The annual cash back counter will reset on August 4, 2026, for all cardholders. Subsequently, it will reset on the account opening anniversary date or the date of the last product change.
Limits per Rogers Card
Here’s the breakdown of earnings caps and their impact on cash back rates. The table below shows the spending threshold that triggers a return to the base rate. Once this threshold is reached, the accelerated rate drops to the card’s base rate for the rest of the year.
| Card | Spending threshold (earnings cap) | Accelerated Rate (before limit) | Base Rate (after limit) |
|---|---|---|---|
| Rogers Red Mastercard | $16,000 | 2% (Rogers customers + US$ purchases) | 1 % |
| Rogers World Mastercard | $26,000 | 2% (Rogers customers + US$ purchases) | 1 % |
| Rogers Red World Elite Mastercard | $61,000 | 2% (Rogers customers) / 3% (US$ purchases) | 1,5 % |
| Rogers World Legend Mastercard | None | Unchanged | Unchanged |
Rogers Red Mastercard®: $16,000
The $16,000 threshold is the lowest in the lineup. This entry-level card has no annual fee. Most cardholders use it as a secondary card or for moderate spending. For many, this threshold won’t change their day-to-day experience.
Beyond $16,000 in annual spending, the cash back rate drops from 2% to 1% on all purchases until the next account anniversary.

Rogers World Mastercard: $26,000
The $26,000 threshold falls within the same range as other cash back cards in the Canadian market. After $26,000 in spending for the year, the rate drops to the base rate of 1%.
Rogers World Elite Mastercard: $61,000
With a threshold set at $61,000, the vast majority of cardholders will not be affected. This level primarily concerns individuals who channel significant business expenses through their personal card.
Beyond the threshold, the rate drops from 2% (or 3% in US$) to 1.5%. With the 50% bonus when redeemed for Rogers purchases, the effective return after the cap still reaches 2.25%. This is still competitive compared to the cash back card market.
Rogers World Legend Mastercard: No Limit
The Rogers World Legend Red Mastercard is the only one exempt from an annual cap on cash back accumulation. If you’re a heavy user of your Rogers card, this is the product Rogers wants to steer you toward.
The upgrade mechanism to a higher-tier card
Here’s an important point Rogers clarified for us. The $16,000, $26,000, and $61,000 thresholds aren’t chosen randomly: they also correspond to the annual spending thresholds required to be eligible for the next card tier.
In practical terms, when you reach your earnings cap, you simultaneously meet the spending requirement to move up to the next level. You can then request a product change to get a higher cap and continue accumulating cash back at the accelerated rate for the rest of the year.
Concrete example with the Red Mastercard
You hold the Rogers Red Mastercard® ($16,000 cap). In September, you’ve already accumulated $16,000 in spending since your last account anniversary. Your rate drops to 1%.
Since you’ve reached $16,000 in annual spending, you’re eligible for the Rogers World Red Mastercard (which requires the same threshold). You can request a product change with Rogers and get a $26,000 cap. Your next purchases return to the accelerated rate of 2%, up to the new cap.
The same principle applies if you then move from the World Mastercard to the World Elite ($61,000 threshold), and then from the World Elite to the Legend (no cap).
Who is Really Affected?
The most affected cardholders are Rogers, Fido, Shaw, or Comwave customers. They are the ones who benefit from the accelerated 2% rate on all their purchases, and not just on US dollar purchases. For cardholders who are not customers of these providers, only the accelerated rate on US$ purchases is subject to the cap.
- Legend Card Exempt: no cap, accelerated rates maintained without limit
- 1.5x Bonus Preserved: the additional 50% bonus when redeeming for Rogers, Fido, Shaw, or Comwave purchases remains unchanged
- Upgrade possible: reaching the cap opens access to the next card tier, with a new cap and a return to the accelerated rate
- Rogers Customers Most Affected: those who benefit from 2% on all purchases will see their cash back capped after the annual threshold
- Interest rate increase: the rate increases from 20.99% to 21.99% on all four cards
- Low cap on entry-level card: the $16,000 threshold can be quickly reached by users who concentrate their spending on this card
Impact on the 1.5x Redemption Bonus
The updated terms do not mention any modification to the 1.5x redemption bonus. Specifically, when you redeem your cash back for eligible purchases with Rogers, Fido, Comwave, or Shaw, you still get 50% additional value. This brings the effective value up to 3% cash back on your accelerated-rate spending.
This bonus also applies to cash back accumulated at the base rate, after exceeding the limit. For example, on the World Elite, the base rate of 1.5% combined with the 1.5x bonus gives an effective return of 2.25%. This is still very good in the Canadian cash back card landscape.
Alternatives to Consider
If these limits concern you, several cash back cards without limits (or with more generous limits) exist in the Canadian market. Consult our page on the best credit cards to compare options based on your spending profile.
For cardholders who primarily use their Rogers card for US dollar purchases (travel, online purchases in the United States), the foreign currency cards category is also worth a look. Some cards offer competitive rates with no conversion fees, and no limits.
Bottom Line
The annual caps on cash back accumulation for Rogers Red Mastercard cards are not a surprise in the current market. More and more Canadian issuers are limiting their accelerated rates to control costs. The majority of cardholders will likely not be affected, especially on the World Elite ($61,000) and World ($26,000) cards.
The most affected profiles are those who combine high spending volume with Rogers customer status. For them, two options: aim for the Legend directly, or follow the upgrade path as caps are reached. For everyone else, the return remains competitive, especially with the 1.5x redemption bonus.
To receive our analyses on credit cards and loyalty programs every week, subscribe to our newsletter.
Rogers Mastercard Cards Earnings Caps – Frequently Asked Questions
What is the cap on the entry-level Rogers Red Mastercard?
The annual threshold is $16,000 in spending, the lowest in the lineup. Beyond it, the cash back rate drops from 2% to 1% on all purchases until the next account anniversary. Since this card has no annual fee, it is often used as a secondary card, but cardholders who concentrate their spending on it can reach this cap quickly.
When do the earnings caps on Rogers cards come into effect?
The annual caps on cash back accumulation come into effect on August 4, 2026. On that date, each cardholder’s counter will be reset to zero.
Is my spending capped on Rogers cards?
No. The cap applies to cash back accumulation, not to spending. You can continue to use your card without limit, but beyond the annual threshold, cash back drops to the card’s base rate.
What is the cap for the Rogers World Elite Red Mastercard?
The annual threshold is $61,000 in spending. Beyond that, the cash back rate drops from 2% (or 3% in US$) to the base rate of 1.5%.
Is the Rogers World Legend Red Mastercard affected by the caps?
No. The Rogers World Legend Red Mastercard is the only card in the Rogers portfolio exempt from any annual cap.
What happens when I reach my Rogers card cap?
Purchases made after reaching the threshold are rewarded at the card’s base rate (1% for Red and World Mastercard cards, 1.5% for World Elite). You can also request a product change to the next card tier to get a higher cap.
How does the upgrade to a higher-tier Rogers card work?
The cap thresholds for each card correspond to the annual spending thresholds required to move up to the next card tier. When you reach your cap, you also meet the requirement for the next level card. You can then request a product change to get a higher cap and a return to the accelerated rate for the rest of the year.
Is the 1.5x redemption bonus with Rogers changing?
No. The additional 50% bonus when redeeming cash back for Rogers, Fido, Shaw, or Comwave purchases remains unchanged. It also applies to cash back accumulated at the base rate.
When does the annual cash back counter reset?
The counter will be reset on August 4, 2026, for all cardholders. Subsequently, it will reset on the account opening anniversary date or the date of the last product change.
Is the interest rate also changing on Rogers cards?
Yes. The interest rate on purchases increases from 20.99% to 21.99% on all four Red Mastercard cards, including the Legend. This change also comes into effect in August 2026.
Are non-Rogers customers affected by the limits?
Only partially. Cardholders who are not Rogers, Fido, Shaw, or Comwave customers only benefit from the accelerated rate on US dollar purchases. The limit applies to this rate, but the majority of their spending (in Canadian dollars) is already at the base rate.
To put these changes in context, see our full guide to credit card spending caps by category.
Our featured card

- Annual fee
- $0 $120No annual fee the first year
- No annual fee the first year
- Our valuation
- $420Milesopedia first-year estimate First-year valueWelcome bonus$300Annual fee rebated$120Total$420Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Milesopedia first-year estimateFirst-year valueWelcome bonus$300Annual fee rebated$120Total$420Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- Welcome offer
- Up to $300
- + First Year Annual Fee Rebate
- Ends Nov 1, 2026
on Scotiabank's website
Our editorial integrity
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.