Questrade vs Wealthsimple: Which Is Better?

Loading article…
If you’re hesitating between Questrade vs Wealthsimple, you’re not alone. These two platforms are among the most popular online brokers for investing in the stock market in Canada. But which one is truly the best for you?
To understand Wealthsimple’s strategy, listen to our podcast interview with its Chief Growth Officer, Simon Lejeune.
In this article, we compare fees, trading tools, self-directed investing, ETFs, financial ecosystem, and investor profiles. You’ll know exactly which platform to choose based on your strategy, transaction frequency, and long-term goals.
On one side, Questrade is a pure online broker offering advanced tools. On the other, Wealthsimple focuses on simplicity, commission-free trading, and an integrated financial ecosystem including a chequing account and credit card.
Before diving into the details, here are the major distinctions.
First, Questrade is a comprehensive traditional broker, designed for self-directed investing and active investors. Next, Wealthsimple is a simplified platform, mobile-oriented, integrated with other financial services.
Next, the management of U.S. dollars constitutes a structural difference. Questrade allows you to maintain USD balances in most accounts. Wealthsimple charges 1.5% conversion fees unless you hold a plan that includes a USD account.
Furthermore, trading tools are more advanced at Questrade. Conversely, Wealthsimple favors a streamlined and user-friendly interface.
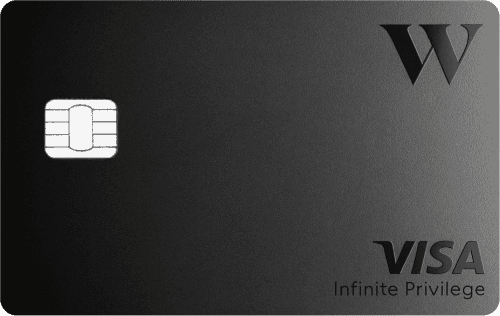
Finally, Wealthsimple offers a complete financial ecosystem, including a chequing account and Visa Infinite card, while Questrade is a pure broker.
| Feature | Questrade | Wealthsimple |
|---|---|---|
| Stocks & ETFs | Commission-free | Commission-free |
| Options | $0/contract on U.S. equity options; US$0.99/contract on U.S. index options (from September 28, 2026); CA$0.99/contract on Canadian options | Commission-free, no per-contract fee |
| USD account | Yes, avoids repeated conversion | Requires a paid plan ($10/month under $100,000 in assets) |
| Currency conversion | ~1.5%, Norbert’s Gambit long established | ~1.5%, Norbert’s Gambit in beta since March 2026 (web only, $9.95 plus tax per transaction) |
| Trading tools | Advanced (Questrade Edge Desktop/Web) | Simplified, mobile-first interface |
| Banking ecosystem | None yet (Questbank launch announced, no date yet) | Chequing account and Visa Infinite credit card |
| Best for | Active traders, frequent USD investors | Beginners, integrated ecosystem seekers |
Both platforms advertise commission-free transactions on stocks and ETFs. However, the reality deserves nuance.
At Questrade, buying stocks and ETFs is commission-free. Selling stocks and ETFs has also been free for several years. There are no inactivity fees.
At Wealthsimple, buying and selling stocks and ETFs are commission-free. There are also no inactivity fees.
At first glance, perfect equality. However, the gap appears as soon as we talk about currencies and options.
At Questrade, per-contract fees depend on the type of option, as of September 2026:
At Wealthsimple, equity options trading is also offered commission-free with no per-contract fees.
On U.S. equity options, Wealthsimple and Questrade are therefore tied, with no per-contract fees. At Questrade, only Canadian and U.S. index options still carry a fee, and Questrade Plus subscribers get cash back on every U.S. equity options contract.
However, Questrade may remain relevant for experienced options traders seeking advanced tools, better management of complex strategies, or more specialized features.
At Questrade, conversion fees are approximately 1.5%. However, you can hold U.S. dollars and use strategies like Norbert’s Gambit to reduce fees.
At Wealthsimple, conversion is also approximately 1.5%. However, without a plan that includes a USD account, each U.S. transaction involves automatic conversion.
Therefore, for frequent investing in U.S. stocks, Questrade often becomes more economical in the long term.
Both platforms allow self-directed investing, but the experience differs considerably.
Questrade offers Questrade Edge Desktop and Edge Web. You have access to advanced charts, technical indicators, and detailed market data.
Conversely, Wealthsimple offers a simplified interface with basic charts. The goal is ease of use rather than analytical depth.
Therefore, for an active or experienced investor, Questrade offers more tools.
Wealthsimple excels on mobile. The app is intuitive, fast, and designed to simplify investing.
Questrade also offers a mobile app, but the experience is more oriented toward functionality than simplicity.
Thus, for a beginner or passive long-term investor, Wealthsimple may seem more user-friendly.
If you invest in U.S. stocks, this section is crucial.
Questrade allows you to open registered and non-registered accounts with a USD balance. You can hold your U.S. currency and avoid repeated conversions.
Wealthsimple requires a paid plan to maintain a USD balance. Otherwise, each U.S. stock transaction triggers a conversion.
Currently, both brokers allow Norbert’s Gambit: Questrade has offered it for a long time with no particular additional fees, while Wealthsimple has offered it since March 2026, though still in beta (web only, with a $9.95 plus tax journaling fee per transaction).
Consequently, if you invest regularly in the United States, Questrade offers more flexibility for now.
This is where Wealthsimple clearly stands out. In addition to brokerage, Wealthsimple offers:
You can consult our guide on the Wealthsimple chequing account and our analysis of the Wealthsimple credit card.
Conversely, Questrade does not offer integrated banking services. It remains focused on brokerage for now. However, Questrade obtained approval for a federal banking licence for Questbank in November 2025, which could transform its platform into a comprehensive financial ecosystem. As of October 2026, the Questbank website still describes its launch as coming soon, with no specific date.
Thus, if you want to centralize your finances in a single ecosystem, Wealthsimple has an advantage.
For a long-term investor in ETFs, both platforms allow commission-free purchases.
However, Questrade offers more tools to build a diversified portfolio and analyze data. Wealthsimple facilitates quick execution and simple management.
If you use index ETFs and invest a few times per year, both options are viable.
To learn more, consult our Questrade review and our guide on Wealthsimple.
The choice between Questrade vs Wealthsimple depends primarily on how you invest, your level of experience, and your exposure to U.S. markets.
For a new investor who wants to buy their first ETFs or a few Canadian stocks, Wealthsimple offers a more intuitive experience. The interface is simple, the mobile app is user-friendly, and the absence of commission facilitates the first steps.
For a long-term index strategy with few annual transactions, both platforms are suitable. However, Wealthsimple favors simplicity of execution, while Questrade offers more analytical tools to build a more structured portfolio.
For a portfolio exposed to U.S. stocks, Questrade has the advantage. The ability to hold USD balances and avoid repeated conversions reduces costs in the long term.
For someone who analyzes markets, uses advanced charts, and executes multiple transactions per month, Questrade is generally better suited. Its Edge platform offers more technical depth.
For an investor who regularly trades options, both platforms now charge $0 per contract on U.S. equity options. Questrade stands out mainly for its specialized tools for complex strategies and its Questrade Plus cash back of CA$0.05 per contract.
For centralized management combining investing, cash, and credit card, Wealthsimple offers a more comprehensive integrated approach.
on Wealthsimple's website
In summary, in the Questrade vs Wealthsimple duel, there is no universal winner.
Your decision should reflect your transaction frequency, your exposure to U.S. markets, and your level of experience. To learn more, subscribe to our newsletter and compare the best credit cards to optimize your finances alongside your investments.
The right credit card choice depends on your profile – income, expenses, objective (travel, cash back, balance transfer). To compare options according to your criteria, use our credit card comparator. You can also consult our ranking of the best credit cards of the month, updated monthly by the Milesopedia team.
Questrade is a Canadian online broker that allows you to invest in stocks, ETFs, options, and other products through registered and non-registered accounts.
Yes, but they are limited. Stocks, ETFs, and U.S. equity options are free of commissions and per-contract fees. However, fees apply to Canadian options (CA$0.99 per contract), U.S. index options (US$0.99 per contract from September 28, 2026), and currency conversions (1.5%).
Questrade generates revenue through, among other things, fees on Canadian and U.S. index options, currency conversion fees, and certain administrative fees. Since July 30, 2026, U.S. equity options no longer earn it any per-contract fees.
Wealthsimple is a Canadian platform offering Wealthsimple Trade (formerly Self-directed Investing), managed portfolios, and integrated banking services.
It depends. Questrade is often preferable for active investors and USD accounts, while Wealthsimple is better suited for beginners and those who want an integrated ecosystem.
Yes, within the limits of the Canadian Investor Protection Fund (CIPF). Questrade and Wealthsimple are both members. If the broker becomes insolvent, CIPF covers missing property up to $1 million for all general accounts combined (cash, margin, TFSA, FHSA), $1 million for retirement accounts (RRSP, RRIF), and $1 million for RESPs. CIPF does not protect against a drop in the value of your investments, and crypto assets are excluded.
Yes. As of September 2026, both brokers offer self-directed RRSPs, individual or family RESPs, TFSAs, and FHSAs.
Yes, you can hold accounts at both. However, your TFSA contribution room applies to all your TFSAs combined: opening a second account does not double your limit. To move a TFSA, use a direct transfer between institutions rather than a withdrawal.
on BMO's website
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.