**Most Canadian credit cards add 2.5% to every purchase in a foreign currency. A card with no foreign transaction fee skips that surcharge: on $5,000 of travel spending, you keep $125.** Our catalogue lists 12 Canadian credit cards that charge no foreign transaction fee. Here is the best one for your profile: cash back, Scene+ points, airport lounges, no annual fee, or travellers 65 and over.
A card with no foreign transaction fee only applies the network exchange rate, set by Visa, Mastercard or American Express. The annual fee pays for itself quickly: at 2.5% saved, a $150 card is covered once you spend $6,000 a year in foreign currencies.
The table below shows our selection. Further down, you will find the best choice for each profile, then the math on what you actually save based on your travel budget.
Fees, earn rates and welcome offers in effect on November 3, 2026, according to each issuer's website. Offers change often: check the issuer's terms before applying. Milesopedia may be compensated when you get a card through our links; this does not change our ranking by profile.
Cash back on every purchase
Winner: the Wealthsimple Visa Infinite+ Card. You earn 2% on everything, with no categories and no cap, and that rate also applies to purchases abroad. If you spend $5,000 while travelling, you collect $100 in cash back instead of paying $125 in fees with a regular card.
The $240 fee disappears if you hold $100,000 in assets with Wealthsimple or direct deposit $4,000 a month. Otherwise, you need $12,000 a year in purchases at 2% to cover the fee.
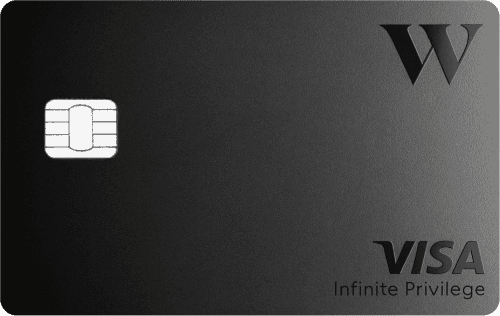
Alternative with lounges: the Wealthsimple Visa Infinite Privilege Card, at the same price, for a personal income of $150,000 or a household income of $200,000.
Wealthsimple Visa Infinite+ Card →Wealthsimple Visa Infinite Privilege Card →Best cash back credit cards →Wealthsimple insurance in Quebec: activation and limits →Scene+ travel points
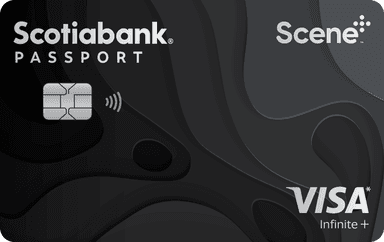
Winner: the Scotiabank Passport Visa Infinite+ Card. For $150 a year, it combines Scene+ points on groceries and dining, no foreign transaction fee and 6 lounge visits. Visa is accepted almost everywhere, which makes it our default travel card.
You apply your points to any travel purchase at 1,000 points for $10. The 15,000 points earned after $3,000 in purchases in 3 months are worth $150 and already cover the first-year fee; 20,000 more points follow after $10,000 in 6 months.
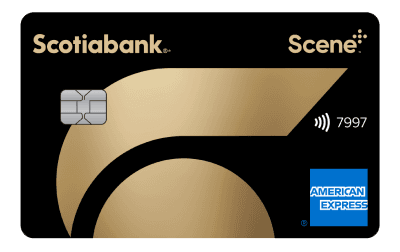
Alternative for groceries: the Scotiabank Gold American Express Card. At $120, it earns up to 6 points per dollar on groceries in Canada. Abroad, it earns only 1 point per dollar, but you still avoid the 2.5%.
Scotiabank Passport Visa Infinite+ Card →Scotiabank Gold American Express Card →Best Scene+ credit cards →Frequent travellers and airport lounges
Winner: the Scotiabank Platinum American Express Card. You earn 2 points per dollar on all purchases, foreign currency included, and 10 visits a year to Priority Pass and Plaza Premium lounges. At $399, it pays off if you travel several times a year.
Visa alternative: the Scotiabank Passport Visa Infinite Privilege Card. $599 a year, 3 points per dollar on travel, 2 points on dining and entertainment, 10 lounge visits per cardholder and a $250 annual credit on your first travel booking through Scene+ Travel. Its offer goes up to 80,000 points: 40,000 after $3,000 in 3 months, 30,000 after $20,000 in 6 months, then 10,000 for a purchase in the 14th month, for accounts opened from November 2, 2026, to January 3, 2027.
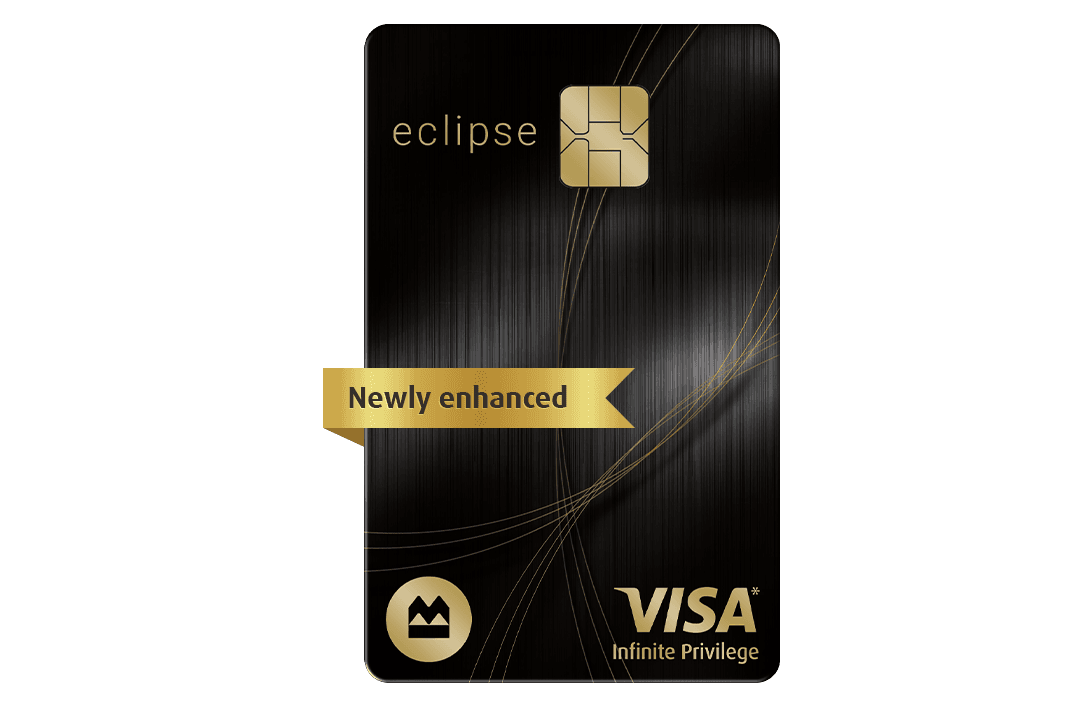
BMO points alternative: the BMO eclipse Visa Infinite Privilege Card. Since November 2, 2026, it no longer charges a foreign transaction fee. For $599 a year, you earn 5 BMO Rewards points per dollar on travel (flights, hotels and car rentals), groceries, gas, and health and wellness, plus 10 airport lounge passes and a $200 annual travel credit. Its offer goes up to 200,000 points, subject to BMO's terms. BMO requires a personal income of $150,000 or a household income of $200,000.
Cash back alternative: the Rogers Red World Legend Mastercard. $495 a year, 2% cash back on purchases in Canada and in foreign currencies for eligible Rogers customers, and 6 Plaza Premium lounge passes a year.
Scotiabank Platinum American Express Card →Scotiabank Passport Visa Infinite Privilege Card →BMO eclipse Visa Infinite Privilege Card →Rogers Red World Legend Mastercard →Best travel credit cards →Travellers 65 and over: travel insurance
Check the medical coverage before the 2.5% savings. At Scotiabank, coverage continues after 65, but it gets much shorter. The Passport Visa Infinite+ covers 25 days per trip under 65 and 3 days after. The Platinum American Express covers 31 days under 65 and 10 days after.
For a stay of several weeks down south, these durations are not enough: we recommend separate travel insurance. For the Wealthsimple cards, read the certificate of insurance, which sets the durations and age conditions.
Best travel credit cards →Business spending in foreign currencies
Winner: the Scotiabank Passport Visa Infinite Business Card. It is the business card with no foreign transaction fee in our catalogue. For $199 a year, you earn 1.5 Scene+ points per dollar on business purchases. On $20,000 of foreign currency purchases a year, you avoid $500 in fees, more than the cost of the card.
Scotiabank Passport Visa Infinite Business Card →Best business credit cards →How much you really save
The math is simple: multiply your foreign currency purchases by 2.5%. Here is what you keep each year with a card that charges no foreign transaction fee.
$2,000 in foreign currency (a one-week trip): $50 saved.
$5,000 (two trips a year): $125.
$10,000 (travel plus online purchases in US dollars): $250.
$20,000 (a winter down south): $500.
Then compare that amount with the annual fee. A $120 card is covered from $4,800 in foreign currency purchases, a $150 card from $6,000, a $399 card from $15,960. Below those thresholds, points, cash back and insurance have to make the difference.
Guide: how to save on foreign currency transactions →Credit card comparison tool →How to choose your card
Always pay in the local currency. At the terminal or ATM, decline the conversion to Canadian dollars offered by the merchant. That rate is often worse, and it cancels out the advantage of your card.
Carry two networks. American Express is accepted less widely than Visa and Mastercard in some countries and at many small merchants. If your main card is an Amex, add a Visa with no foreign transaction fee.
Avoid ATM withdrawals with a credit card. A withdrawal is a cash advance: interest starts on day one, even with no foreign transaction fee.
Consider prepaid cards too. If you do not want a new credit card, a prepaid card with no foreign transaction fee does the job for a trip.
To get new card offers and our analysis, create your free member account.
Best prepaid cards with no foreign transaction fees →Create your free Milesopedia member account →All the best credit cards →Frequently Asked Questions
What is the best credit card with no foreign transaction fee in Canada?
It depends on your profile. For cash back, the Wealthsimple Visa Infinite+ Card gives 2% on everything, in foreign currencies and Canadian dollars alike. For travel points, the Scotiabank Passport Visa Infinite+ Card ($150) combines Scene+ points with 6 lounge visits. For lounges, the Scotiabank Platinum American Express Card offers 10 visits a year.
How much is the foreign transaction fee on a credit card?
Most Canadian credit cards add 2.5% to the amount converted into Canadian dollars. On a $1,000 purchase in a foreign currency, you pay $25 more. A card with no foreign transaction fee only applies the exchange rate of the Visa, Mastercard or American Express network.
Is there a credit card with no annual fee and no foreign transaction fee?
Yes, but the choice is short. The Home Trust Preferred Visa has no annual fee and no foreign transaction fee and earns 1% cash back; it is not available to Quebec residents. Capital One's Quicksilver World Mastercard also has no annual fee and no foreign transaction fee. Finally, the $240 fee on the Wealthsimple cards is waived with $100,000 in assets or $4,000 a month in direct deposits.
Do online purchases in US dollars count?
Yes. An online purchase billed in US dollars or euros triggers the same 2.5% fee, even if you never leave Canada. A card with no foreign transaction fee therefore saves you that fee on Amazon.com, subscriptions billed in US dollars or hotel bookings abroad.
Do you earn the same points on foreign currency purchases?
Not always. The Scotiabank Gold American Express Card earns only 1 point per dollar on foreign currency purchases, while it earns up to 6 on groceries in Canada. The Scotiabank Platinum American Express Card keeps its 2 points per dollar, and the Wealthsimple cards keep their 2% cash back.
Is a no foreign transaction fee card worth its annual fee?
Yes, once your foreign currency purchases pass the break-even point. At 2.5% saved, a $120 card pays for itself from $4,800 of foreign currency purchases a year, and a $150 card from $6,000. Points, cash back and lounge visits come on top of that.
Can you withdraw cash abroad for free with these cards?
An ATM withdrawal with a credit card is a cash advance: interest applies from the day of the withdrawal and cash advance fees are added, even with no foreign transaction fee. For cash while travelling, compare your debit card or a prepaid card with no foreign transaction fee instead.
Should you pay in Canadian dollars or in the local currency abroad?
Always pay in the local currency. When a terminal or ATM offers to charge you in Canadian dollars, it applies its own conversion, which is often less favourable. With a card that charges no foreign transaction fee, the local currency gives you the network rate, with no surcharge.