Business Card With No Preset Spending Limit: the Only 2 in Canada
Two business cards in Canada work with no preset spending limit, both from American Express. How Amex approves each purchase, how to check your spending power before a big order, and which small business this setup suits.
Two business cards in Canada carry no preset spending limit: the Business Platinum Card and the Business Gold Rewards Card, both from American Express. The amount you can put on the card adjusts to your spending and payment habits. In exchange, the balance is settled in full at every statement.
Our view: among the business credit cards available in Canada, this setup serves a small business whose purchases swing widely from one month to the next. You know the scene. A supplier sends an invoice bigger than usual, the order book justifies it, and the card's limit is what decides. Here, that invoice goes through without a call to the bank.
Two business cards with no preset limit
American Express splits its business cards into two families. On one side, the charge card is settled in full each month and shows no ceiling set in advance. On the other, the credit card carries a credit limit set when the account opens and an interest rate on any balance carried forward.
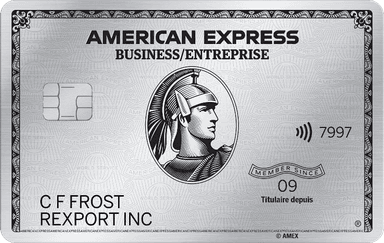
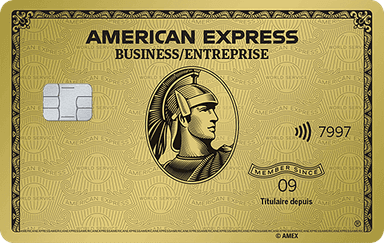
Here are the four business cards American Express offers in Canada, with their family and their fee.
| Card | Type | Annual fee | Employee card | Spending power |
|---|---|---|---|---|
| Business Platinum Card® from American Express | Charge card | $799 | $250 per Platinum employee card, or $0 per Gold employee card (99 maximum) | No preset spending limit |
| American Express® Business Gold Rewards Card® | Charge card | $199 | $50 | No preset spending limit |
| American Express® Aeroplan®* Business Reserve Card | Credit card | $599 | $199, or $0 for the no-fee version | Credit limit set at opening |
| Marriott Bonvoy® Business American Express®* Card | Credit card | $150 | $50 | Credit limit set at opening |
At RBC, TD, Scotiabank, CIBC, BMO and National Bank, the business card comes with a credit limit set when the account opens. The choice therefore comes down to the two charge cards above.
| Credit card | Annual fee | Welcome offer | |
|---|---|---|---|
How Amex approves each purchase
Your spending power is recalculated on every transaction, from your record and your payment history. American Express states that purchases are approved based on a variety of factors, including your current spending patterns, payment history, credit record and the financial resources known to them.
This dynamic spending power adapts to how the card is used. It can therefore grow over time, as long as payments arrive on time and the credit record stays in good shape.

Three things change in practice for a small business.
- Spending power that grows with use: American Express adjusts it based on how the card is used and on payments received on time.
- An amount confirmed purchase by purchase: the available room does not read like a conventional credit limit, it is confirmed at the moment of approval.
- Proof of resources on occasion: American Express notes that proof of financial resources and a guarantee may be required from time to time.
How to check your spending power
A big order deserves preparation. American Express puts a Check Spending Power tool in the online account and in the Amex app: it shows the amount the card will approve, before you reach the till. For a heavier file, the business line answers at 1-877-891-0821, Monday to Friday, 9 a.m. to 5 p.m. ET.
The balance is settled in full monthly
Reassuringly, it does not all land at once. The Pay Over Time option lets you choose your amount at the due date: the full balance, the minimum due, or anything in between. The rest goes by the name pay-in-full balance and is settled at every statement.
Rates frame that flexibility. The preferred rate of 21.99% applies to the Pay Over Time balance. A pay-in-full balance left unpaid, on the other hand, carries a 30% rate.
Payment regularity counts too. Two missed payments in twelve months take the Pay Over Time rate to 25.99%, and three or more take it to 29.99%. These rates apply from the day the account opens.
Up to 55 days to pay a purchase
The Business Gold Rewards Card advertises up to 55 interest-free days between the purchase and the payment due date. In practice, a purchase charged the day after the statement date gets the full window.
Take a $30,000 supplier invoice, charged to the card the day after the statement. The money then stays in the business account for close to eight weeks. Along the way, that invoice earns 30,000 Membership Rewards points, or about $300 in statement credits.
The same invoice on a business credit card eats into the available limit until it is paid. That is exactly the difference sought by businesses where a single order represents several weeks of revenue.
Which business this card suits
This setup does the most good for a business whose purchases swing widely and whose cash flow keeps up. Three situations benefit the most.
- Seasonal or irregular purchases: a $5,000 month followed by a $60,000 month calls for no limit increase and no call to customer service.
- A supplier that invoices big: a single order of several tens of thousands of dollars goes through without eating a ceiling set last year.
- A growing business: spending power follows the account's payment history instead of being renegotiated at every stage.
The American Express Business Gold Rewards Card remains the entry point: $199 a year and 1 point per dollar on every purchase. On top of that come 10,000 bonus points per calendar quarter from $20,000 in net purchases, or up to $400 in value a year. Its welcome offer reaches 70,000 points, about $700 in statement credits: 50,000 points after $7,500 in purchases over the first 3 months, then 20,000 more once $30,000 is reached over 12 months. Put another way, the first year leaves $501 in net gain once the fee is deducted.
- Annual fee
- $199
- Our valuationMilesopedia first-year estimate First-year valueWelcome offer$1,190Total$1,190Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- $1,190
- Welcome offerAfter $30,000 in 12 months
- Up to 70,000 points
on American Express's website
Apply with confidenceCheck whether your application will be approved before you submit it, with no impact on your credit score*When you apply for a personal American Express Credit Card, we will tell you whether you are eligible without affecting your credit score. So you can apply with confidence.*Instant decisions are only available for consumer Card applications (also called “personal Cards”).
For a business that travels often, the Business Platinum Card from American Express changes scale: $799 a year and 1.25 points per dollar on every purchase. Its welcome offer reaches 120,000 points, about $1,200 in statement credits, in two stages: 80,000 points after $15,000 in purchases over the first 3 months, then 40,000 points for a purchase made between the 15th and 17th month. In the first year, the 80,000 points (about $800) therefore just cover the $799 fee. The $200 annual travel credit, used on a booking through American Express Travel, is what puts the card ahead.
- Annual fee
- $799
- Our valuationMilesopedia first-year estimate First-year valueWelcome offer$1,360Total$1,360$680 deferred bonus, excluded from the first-year estimate and not counted in this total.Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- $1,360
- Welcome offerAfter $15,000 in 3 months
- Up to 120,000 points
on American Express's website
Apply with confidenceCheck whether your application will be approved before you submit it, with no impact on your credit score*When you apply for a personal American Express Credit Card, we will tell you whether you are eligible without affecting your credit score. So you can apply with confidence.*Instant decisions are only available for consumer Card applications (also called “personal Cards”).
Business credit card: when to prefer it
A limit set in advance has its virtues too. It gives a known amount before you even place an order, and it lets you spread a large purchase over several months. American Express sums up both families in its own comparison of business credit and charge cards.
| What changes | Charge card | Credit card |
|---|---|---|
| Spending limit | No preset limit | Limit set when the account opens |
| Balance at the due date | Settled in full every month | Can be carried from one month to the next |
| Interest-free window | Up to 55 days | Interest as soon as a balance is carried |
| Rate | 30% on a pay-in-full balance left unpaid | 21.99% on the balance carried |
| Amex business cards | Business Platinum, Business Gold Rewards | Aeroplan Business Reserve, Marriott Bonvoy Business |
Three cases lean that way. First, a business that would rather repay a large acquisition over six months. Next, a team that wants to know its exact ceiling before placing an order. Finally, a supplier list where some names do not accept American Express.
The CIBC Aventura Visa Card for Business covers that need, at $180 a year, with a conventional credit limit and up to three authorized users refunded two years running. One point does weigh on the decision: CIBC asks for $35,000 in personal income, where the two American Express charge cards ask for none and assess the business instead. If you are self-employed, three business credit cards with no personal income requirement also do the job.
- Annual feeNo annual fee the first year
- $0 $180
- First year free
- Our valuationMilesopedia first-year estimate First-year valueWelcome offer$700Annual fee rebated$180Total$880Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
- $880
- Welcome offer+ Annual Fee Rebate for the First 2 YearsAfter $40,000 in 12 months
- Up to 70,000 points
on CIBC's website
Financing your small business's growth? See our guide to Small Business Month: BDC Week and federal loans for the financing programs worth knowing.
Conclusion
All told, a small business that buys big and irregularly is no longer stopped by a ceiling decided when the account opened. The trade-off fits on one line: the pay-in-full balance comes due at every statement, and no amount is guaranteed in advance.
Only two cards work this way in Canada. The Business Gold Rewards Card at $199 covers most small businesses. The Business Platinum Card, for its part, earns its keep once business travel and premium benefits enter the calculation.
To follow business card offers every week, subscribe to our newsletter.
Business card with no preset limit - Frequently Asked Questions
What is a business card with no preset spending limit?
Which business cards have no preset limit in Canada?
Is spending power unlimited?
How do I know whether a large purchase will go through?
What interest rates apply to these two cards?
Is a personal income required for these cards?
How much does an employee card cost on these two cards?
Does a card with no preset limit suit a sole proprietor?
Learn more
- Compare credit cards to place the business options side by side.
- American Express Membership Rewards points: what they are worth and how to redeem them.
- Business cash flow managed with a credit card, to go further than the payment window alone.
- How to apply for an Amex business card, step by step.