
National Bank MC1 Card: How My First Credit Card Became a World Elite
At 18, I got the National Bank MC1 card on my father's advice. Today, that same account is a World Elite card, and it still carries my entire credit history.
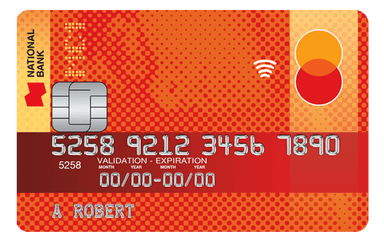
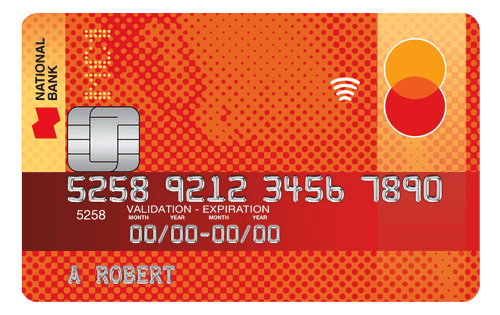
I was 18 when my father told me: "Get a credit card as soon as you can." He wasn't talking about shopping. He was talking about credit. My first card was the National Bank MC1® Mastercard®, a card with no annual fee and no minimum income. Years later, it's still the same account, except today it carries the World Elite name.
Here is my story, and above all what the National Bank MC1 card can do for you if you are just starting out financially. To compare it with other options, also see our ranking of the best credit cards in Canada.
My Father's Advice at 18
In Quebec, the age of majority is 18 (19 in some provinces). From that point, you can sign a credit agreement on your own. My father saw that milestone as a starting line. In his view, every month I waited was a month of credit history lost.
I had almost no income. I was studying and mostly working in the summer. So I needed a simple card, with no annual fee and no proof of a big salary. The MC1 checked every box.
His second piece of advice mattered just as much: pay the full balance, every month. A credit card only builds your file if you pay it back on time. Otherwise, it can damage it just as quickly.
Why Build Your Credit From Age 18
Your credit report is your financial reputation. Equifax and TransUnion record your accounts, your payments and the length of your history. The longer and cleaner that history, the more easily doors open. To go further, read our guide on how to build a good credit score as a student.
My father gave me three concrete examples: a cellphone, an apartment and a car. Over the years, I found many more, especially when travelling.
Where Your Card and Your Credit Matter
- Your cellphone: carriers generally check your credit before approving a plan with a device. A phone paid in instalments is a debt to the carrier that you repay every month.
- Your apartment: many landlords ask for your permission to check your credit report before signing a lease. An empty file can cost you an apartment against another applicant.
- A car, later on: one day, you may want to finance a vehicle. Let's be clear, financing a car is rarely a good financial move. But if you need one, a good file will give you access to better rates.
- Car rentals: most agencies require a credit card in the main driver's name, at home and abroad. With a debit card, the rental is often refused or comes with stricter conditions.
- Hotels: at check-in, the hotel usually asks for a credit card to guarantee the room and hold an amount for incidentals.
- Booking a trip: flights, all-inclusive packages, excursions. A credit card is often the simplest way to pay, and sometimes the only one accepted.
- School and beyond: a line of credit, then a mortgage. A long, clean history makes each of these applications easier.
Travel taught me that lesson very quickly. I remember an all-inclusive trip down south that cost about $1,000 at the time. I needed a credit card to pay for it, but the price was higher than my limit. So I made a payment on my card in advance, before booking. That deposit increased my available credit, and I was able to pay for my trip.

The National Bank MC1 Card at a Glance
The MC1 is National Bank's entry-level card. It earns neither points nor cash back. On the other hand, it costs $0 a year and requires no minimum income. For an 18-year-old, that is exactly what you need.
| Feature | National Bank MC1 card |
|---|---|
| Annual fee | $0 |
| Additional cards | $0 |
| Minimum income | None |
| Minimum credit limit | $500 |
| Purchase interest rate | 20.99% |
| Cash advance and balance transfer rate | 22.49% |
| Foreign transaction fee | 2.5% |
| Rewards program | None |
| Insurance | Purchase protection (90 days) and extended warranty (1 year) |
The card also includes 90-day purchase protection and a one-year extended warranty. Mastercard's Zero Liability program protects you against unauthorized purchases.
The most important feature is the 21-day grace period. If you pay the full balance within 21 days of your statement date, you pay no interest on your purchases. So the 20.99% rate never affects you if you pay everything, every month.
From MC1 to Platinum, Then World Elite
My card changed names twice. Yet I never applied for a new card. At each step, I asked National Bank to upgrade my account to a higher-tier product.
Platinum During My Studies
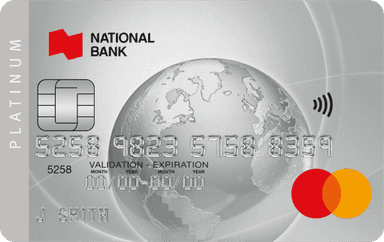
While I was in school, I worked every summer. I had a little more money and wanted to start earning points. So I moved to the National Bank Platinum Mastercard®.
The Platinum costs $70 a year and requires no minimum income. It earns points on your purchases, which the MC1 does not.
World Elite Today
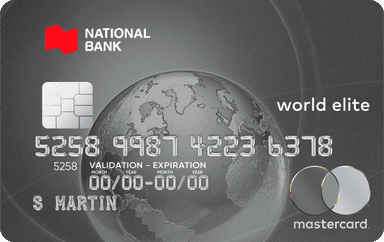
Today, I travel a lot. So I upgraded my card to the National Bank World Elite® Mastercard®. Among National Bank's cards, it was the one that gave me the best return in points. Its annual fee is $150.
On the other hand, the card offers an annual travel credit of $150 for certain eligible travel expenses. If I use it in full, it covers the annual fee completely. For me, the card costs nothing.
On the points side, it earns National Bank À la carte Rewards points at these rates:
- Groceries and restaurants: 5 points per dollar, up to $2,500 in total spending per statement, then 2 points per dollar
- Gas, travel and recurring payments: 2 points per dollar
- Other purchases: 1 point per dollar
Note that the World Elite requires a personal income of $80,000 or a household income of $150,000. If you are just starting out, it is not the card to apply for.
| Credit card | Annual fee | Welcome offer | |
|---|---|---|---|
Change Cards Without Losing Your History
This is the most useful lesson from my journey. When you change cards at the same financial institution, you don't close your account. You change the product attached to that account.
As a general rule, your credit report therefore keeps showing the original opening date. In my case, my World Elite carries the history of the MC1 I opened at 18. The length of your history counts in the calculation of your credit score. Keeping your oldest account open therefore has real value.
On the other hand, cancelling your first card to apply for a new one elsewhere wipes out that advantage. The new card starts from zero, and the application adds a credit inquiry to your file. Before you close anything, read our guide on how to cancel a credit card safely.
National Bank's Offer for Professionals
During my accounting studies at HEC Montréal, I discovered National Bank's offer for professionals. It gives you access to chequing accounts with no fixed monthly fees and to lines of credit at preferred rates, provided you hold an eligible rewards card: the World Elite, the World or the Platinum.
Of the three, I chose the World Elite because it gave me the best return in points and I travel a lot. Accounts, lines of credit, conditions by profession: all the details are in our guide to the National Bank offer for professionals.
My Tips for Your First Card
If you are 18 or a student, here is what I would do again without hesitation:
- Start early, with a no annual fee card like the MC1.
- Start with your own bank. Apply for your first card at the institution where you already have your bank account. It knows your deposits and your history with it, which can make approval easier. Your payments also take just a few clicks, from one account to the other.
- Pay the full balance on every statement. Set up an automatic payment if you are afraid of forgetting.
- Use little of your limit. With a $500 limit, keep your balance well below it.
- Don't close your first card. Instead, ask your bank to upgrade it to a higher-tier product when your income grows.
- Choose a bank you can grow with. My path worked because National Bank had a card for every stage.
No Credit Yet or Application Declined?
A first refusal is nothing dramatic. With no history, some applications don't go through the first time. Here are the simplest ways to get started anyway:
- Talk to your advisor: at the bank where you have your account, an advisor can steer you toward the most accessible card or offer you a lower limit to start.
- A secured credit card: you deposit an amount that serves as collateral and becomes your limit. It works like a regular card and lets you build a history.
- Authorized user: a parent can add you to their card. It is useful for learning how to manage a card, but that status doesn't build your own file in the same way.
- Wait before reapplying: every application leaves an inquiry on your file. Wait a few months and fix whatever blocked you. Our guide Applying for a new card: from declined to approved walks you through the steps.
- Avoid for building credit: prepaid cards. They are handy for paying online, but they are not credit, so they don't help your file.
To see other options suited to students, check our ranking of the best student credit cards and of the best National Bank credit cards.
Read next across our sites

Conclusion
My father's advice fit in one sentence, but it stayed with me for years. The National Bank MC1 card never earned me a single point. But it gave me something rarer: a long, clean credit history. That history is what opened the door to the Platinum, then the World Elite.
If you are starting your financial life, the MC1 remains a simple, free way to take the first step.
To get our credit card analyses and best strategies every week, subscribe to the Milesopedia newsletter.
Frequently Asked Questions About the National Bank MC1 Card
Does the National Bank MC1 card have an annual fee?
No. The National Bank MC1® Mastercard® has no annual fee, and additional cards are free as well. That is what makes it a good first card: you build your credit file without paying to do it. However, a 2.5% foreign transaction fee applies to purchases in foreign currencies. For travel, a card with no foreign transaction fees can be a better fit.
What income do you need to get the MC1 card?
The MC1 card requires no minimum income. It is still subject to National Bank's credit approval, but it is designed precisely for people who are starting their history. The minimum credit limit is $500. If you are a student, our guide on how to build a good credit score as a student gives you more ideas.
Does the MC1 card earn points or cash back?
No. The MC1 has no rewards program. Its role is to give you access to credit simply and at no cost. When your income grows, you can ask National Bank to upgrade your account to a card that earns points, such as the Platinum or the World Elite.
Do I lose my credit history if I change cards?
As a general rule, no, if you stay with the same financial institution. Upgrading your card changes the product, not the account. Your file therefore usually keeps the original opening date. Confirm it with your advisor before the transaction. Cancelling the card to apply for another one, however, starts over from zero. To learn more, read what a good credit score is in Canada.
At what age can you get a credit card in Canada?
You can apply for a credit card in your own name once you reach the age of majority: 18 in Quebec, Ontario, Alberta, Manitoba, Saskatchewan and Prince Edward Island, and 19 in the other provinces and the territories. Before that age, you can become an authorized user on a parent's card, but that status doesn't build your own history in the same way. See our ranking of student cards to compare.
Which National Bank card should you choose after the MC1?
It depends on your income and your travel habits. The Platinum is a good fit if you want to start earning points with no income requirement. The World Elite becomes worthwhile when you travel and meet its income threshold, which is $80,000 personal or $150,000 household. Its annual travel credit can then offset its annual fee. Compare them on our page of the best National Bank credit cards.