One of the biggest rules in personal finance regarding credit cards, is to honor your balance entirely, every single month! However, things happen, some circumstances may prevent full payments to be made, and you can find yourself easily pushed into the credit card debt.
Credit card debt is not easy to deal with, the interest fees continue each day that goes, your debt obligations pile up, and your minimum payments hardly touch the principal. The struggle can be real!
If monthly interest changes won’t let you pay off this debt, you might need to consider using a balance transfer credit card, to help you eradicate your debt once and for all.
What is a balance transfer credit card?
Consumers who want to move the amounts owed to a credit card, with a significantly lower promotional interest rate and better benefits, usually make credit card balance transfers. A balance transfer card is an actual credit card that offers a very low introductory interest rate for an already fixed promotional or introductory period (1.99% for example and six months respectively, for example).
Once the transfer is made, you will only be charged for the low interest rate set during the promotional period. After the latter ends, your card’s interest bounces back to its initial levels, that’s the main reason why you need to pay off most of your debt, if not all of it, before that happens. Balance transfer cards can allow you to consolidate other personal loans and lines of credit as well.
The best balance transfer offers available in Canada vary between 0% (which is very rare) and 3.99%. If used correctly, a balance transfer can allow you to save several hundred dollars in interest payments. Find below what those numbers look like for three different credit cards, paid off over 9 months.
Credit Card
Balance
Interest rate
Monthly payment
Time to pay off
Interest paid
Travel credit card
$1,000
19.99%
$130
9 months
$60.23
Rewards credit card
$1,500
21.99%
$180
9 months
$110.57
Balance transfer credit card
$2,500
1.99%
$310 ($130 + $180)
9 months
$14.78
As you can see, taking advantage of a low interest 1.99% offered by balance transfer will allow you to put the same amount of money on your debt each month, while saving up over $150 in the process. That’s how powerful a low interest balance transfer credit card can be!
What’s the catch? Transferring a balance requires carrying a monthly balance (even with a 0% interest rate), which still involves making on-time payments of at least the minimum due on the transfer, and for any new purchases. Fail to do so, and you might end up losing the credit card’s introductory Annual Percentage Rates (APR) on your transferred balances as well as the grace period while suffering from surprise interest charges -and probably penalty APR- on your next acquisitions.
You need to study your options and avoid high interest rates while paying down debt. In case you’re not familiar with it, a balance transfer APR is the annual percentage rate or interest rate charged to balance transfers. This is a different rate from the ones traced on to purchases, cash advances, and foreign transactions; your cardholder agreement lists the different APR for the different types of transactions.
As it is recommended, always read the fine print before making a decision! You might need to consider the following parameters before getting a balance transfer credit card:
The rate of the Balance Transfer: You need to start by knowing the introductory rate offered, the closer to zero the better. Compared to the standard 19.99% APR, anything between 0% to 3.99% can be worthwhile. You might need to be aware if the card issuer charges a balance transfer fee, which is usually between 1% and 3%.
Promotional Period: The longer the duration of the interest-free period, the better. This way, you will be allowed to pay off your entire balance during the promotional period if you can. However, the regular interest rate rises back to its initial after right after the end of this period.
Annual Fees and Other Benefits: Does the balance transfer card have an annual fee? Are the benefits worth the cost if it does? For an informed decision, verify if the card offers any kind of rewards, like extended warranty, travel insurance, cash back, purchase protection, etc.
During the pandemic, credit card companies are assisting cardholders experiencing financial distress. Card issuers encourage struggling cardholders to reach out and ask about options such as lowering their interest rate, deferring payments, or avoiding late fees.
How do balance transfers affect my credit score?
Balance transfers can affect the credit score positively as well as negatively! It depends on several factors; someone with already good credit can be eligible for some of the best balance transfer cards available.
In general, if you follow a successful strategy regarding balance transfer and you end up paying off the amounts you owe on time, your credit score won’t be harmed. Paying your balance transfer bill on time every month can also boost credit because payment history is the key to have a positive impact on your credit score, and you will be eliminating the debt you’re carrying around while building a great payment history.
The amount of credit allowance offered by the issuer of the balance transfer card may determine how much a credit score improves, the higher the amount available, the more improvement possible.
At worst, the credit score won’t be highly impacted because the overall effect is neutral. But – there is always a but when it comes to Finance – a balance transfer consolidation strategy can hurt your credit score in some cases.
Find below some examples:
If you charge on your other cards and increase your debt instead of getting rid of it, your credit utilization ratio will naturally go up, which means your credit score will eventually decrease.
In case you miss payments because you can’t afford the monthly minimum requirements for one reason or another, or your debt is too big to handle within the period initially set, it will stain the credit history, decreasing your score.
Your score will also decrease if you request several lines of credit within a six-month period. Be aware of applying for a balance transfer credit card around the same time you requested other loans and credit cards! Don’t forget that credit card applications are not grouped together, and each application counts as an individual one with its own credit check. This is not the same case as mortgages and auto loans applications for example, because they can get grouped together if they’re within a small window of time, so it doesn’t impact your credit score negatively as you work to find the best deal. Do your homework and choose the best option before you apply! To minimize the potential negative effect on your credit score, only apply for one card.
The length of credit use isn’t a major factor in credit score calculation and evaluation, but it remains a factor! If you decide to terminate your credit card accounts after the balances’ transfer, it can impact the « age » of your credit history and closing older accounts will cause a decrease in your score. You don’t have to close a credit card just because you eliminated the balance, be strategic about using credit, keep your oldest account open and active, and use it to make a purchase occasionally before paying off the balance in full at the end of the month to skip interest charges. The account will remain in good standing without having debt hanging around.
Our valuationMilesopedia first-year estimateFirst-year valueAnnual fee rebated$29Total$29Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
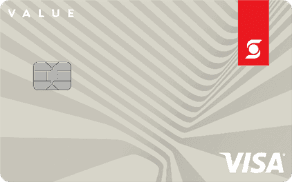
The Scotia minimum Visa Card is one of the best credit cards for balance transfers in Canada.
You can get an introductory interest rate of 0% on balance transfers for the first nine months (with a 1% transfer fee). You pay no annual fee for the first year with this Visa credit card.
What’s more, this Visa credit card offers a low interest rate: 13.99% on purchases, balance transfers and cash advances.
Legal
1 Offer description and terms and conditions: The 0% introductory rate offer on cash advances and the first-year annual fee waiver (the “Offer”) applies only to new Scotia minimum Visa credit card accounts (the “Accounts”) opened between July 2, 2026 and January 3, 2027 (regardless of when you apply for the Account), subject to the terms and conditions below. We will waive the annual fee for the primary card for the first year only. The Offer may be changed, cancelled or extended at any time without notice, and cannot be combined with any other offer.
Description and terms and conditions of the 0% introductory rate offer: The 0% introductory rate offer (the “Rate Offer”) applies to eligible cash advances (including balance transfers and quasi-cash transactions, collectively referred to as “cash advances”), subject to the terms and conditions below. This introductory rate applies for 9 months from that date (the “Promotional Period”). A fee equal to 1% of the amount of any balance transfer made during the Promotional Period applies (minimum fee of $5.00). After the Promotional Period, the interest rate on balance transfers subject to the 0% promotional rate (including any unpaid balance of those cash advances at the end of the Promotional Period) will revert to the applicable preferred interest rate for cash advances (currently 13.99%).
The introductory rate offer is subject to your Account’s cash advance limit. This offer is also based on your approved credit limit as of the date of this offer. This means that if the total of the balances transferred exceeds the approved credit limit, balance transfers may not be processed. This introductory rate offer cannot be used to transfer the balance of another Scotiabank account, or to make a payment or deposit to another Scotiabank account.
Cancellation of the promotional rate: If we do not receive your minimum payment by the due date shown on your statement two times in a row, you will lose the benefits of this special rate offer and your interest rates will revert to the annual rates normally applicable to your Account (24.99% for purchases and 27.99% for cash advances).
Application of payments: Your payment cannot be applied to the balance of your choice. For persons residing in Quebec: Generally, if one or more interest rates apply to your account, we apply payments according to the interest rate(s) that apply to the transactions posted to your account (from the highest rate to the lowest). For persons not residing in Quebec: Generally, if you make a payment greater than the minimum amount shown on your statement, the difference is applied proportionally to the different groups of charges billed to your account. Charges are grouped according to the interest rate applicable to them. Consult your credit card agreement to learn more about how payments are applied to your account.
Description and terms and conditions of the first-year annual fee waiver offer: We will waive the annual fee for the first year only for the primary card, which must occur between July 2, 2026 and January 3, 2027.
Eligibility and exclusions: You cannot take advantage of the Offer if you are currently a primary or secondary cardholder of a Scotiabank personal credit card or if you have been one in the past two years, including if you transfer your balance from an existing Scotiabank personal credit card account (and subject to the exclusions mentioned, persons holding a Scotiabank business credit card are eligible for this offer). By accepting this Offer, you confirm that you meet all eligibility conditions. We reserve the right to revoke this Offer at any time if we believe you do not meet the eligibility conditions, including after its acceptance or obtaining the Account.
Rates and fees: Current annual fees are $29 for the primary card, and additional cards are free (including those issued to co-account holders and additional cardholders). The preferred annual interest rates currently applicable to the Account are as follows: 13.99% on purchases 13.99% on cash advances. All rates, fees, features and benefits described in the application disclosure statement are subject to change.
Savings at Shell
Get up to 3 cents per litre in instant fuel discounts and earn up to 2 cents per litre in Scene+ points value with a Scotiabank Value® Visa* Card linked to a Shell Go+ Account:
Instant 3 cents per Litre Discount on Fuel Purchases (All Grades): Receive an instant 3 cents per litre discount on purchases of fuel (all grades) (“Fuel Purchases (All Grades)”) at participating Shell locations in Canada when you use any eligible Scotiabank debit card or credit card linked to a Shell Go+ Account, up to a maximum of 1,000 litres per month per Scotiabank debit card and per Scotiabank credit card account. This total limit resets at the start of each new month per payment card account. This discount is subject to the Scotiabank Fuel Benefit Terms and Conditions or Tangerine Fuel Benefit Terms and Conditions (as applicable).
Earn up to 2 cents per Litre in Scene+ points Value (Equivalent) on Fuel Purchases: As a Scene+ Member you will automatically earn 1 Scene+ point for each litre in Fuel Purchases (All Grades), and as a Shell Go+ member, automatically earn 1 additional Scene+ point for each litre in Premium Fuel Purchases, made with your linked Scotiabank Value® Visa* Card. This means that for every litre in fuel purchased with your eligible linked card, you can earn the equivalent of up to 2 cents of redeemable Scene+ points value based on a redemption value of $10 for every 1,000 Scene+ points redeemed for fuel purchases at participating Shell Locations. Actual value may be lower depending on how you choose to redeem your Scene+ points. Earn and redemption limits may apply. See the Scene+ Program Terms and Conditions available at sceneplus.ca/terms-and-conditions for full details including redemption options and additional terms.
Note: Highest value of 5 cents per litre assumes a Premium Fuel Purchase made with a Scotiabank Value® Visa* Card linked to a Shell Go+ Account. Actual value will vary depending on whether or not the credit card is linked, fuel grade purchased, cost of fuel at time of purchase, whether or not you are a Scene+ member, and how you choose to redeem your Scene+ points.
Additional 3¢/L at Shell (limited time)
Additional 3¢/L Fuel Discount Offer: Offer valid from October 5, 2026 to December 31, 2026 (“Promotional Period”), eligible Scotiabank credit and debit cardholders enrolled in the Shell Fuel Benefits Program who have linked an eligible Scotiabank payment card (an “Eligible Card”) to their Shell Go+ account will receive an additional instant fuel discount of 3 cents per litre on eligible fuel purchases at participating Shell-branded retail locations in Ontario, British Columbia, Alberta, Saskatchewan, Manitoba, and the Northwest Territories (the “Eligible Provinces”) excluding Shell Flying J locations. Fuel purchases made outside the Eligible Provinces are not eligible for this offer.
To receive the additional fuel discount, customers must pay with their linked Eligible Card at the time of purchase.
The additional fuel discount is in addition to the fuel savings available through the Shell Fuel Benefits Program and may be combined with other eligible fuel discounts, rewards programs, and promotional fuel offers unless otherwise stated in the applicable offer terms and conditions.
The additional fuel discount is available on up to 1,000 litres of eligible fuel purchases per calendar month for each Eligible Card. The 1,000-litre limit resets at the beginning of each calendar month.
The additional fuel discount is non-transferable, is not redeemable for cash, and cannot be substituted or exchanged.
Shell Canada reserves the right to make changes to this offer and to terminate the offer at any time, for any reason and without notice.
All other applicable terms and conditions of the Shell Fuel Benefits Program, Shell Go+ and Scotiabank continue to apply.
Annual fee
Primary card$29
Additional card$0
Annual income required
Individual$12,000
Household$12,000
Conversion fees
2.5%
Earning rate
0xAll spending
Value
2nd Year Value$-29
Pros and Cons of Balance transfers
Credit card balance transfers can be helpful for the right person and scenario, but detrimental otherwise.
Take a step back and evaluate the pros and cons before you ask for a credit card balance transfer, depending on your financial situation! Your credit card must suit your lifestyle.
Advantages of balance transfers
Consolidate Debt
With a credit card balance transfer, you are allowed to combine multiple credit card balances by transferring them to the desired card. Putting all of your credit card debt into one balance through a transfer helps you focus on one payment with one due date, and tackle your debt faster by making single, monthly payments toward the same balance.
Handling one debt is easier to manage several ones, and you won’t have to manage multiple payments and due dates in the case of having multiple credit card balances.
Lower Interest Rates
Credit card balance transfers are mainly interesting because they offer the possibility of saving money on interest. What does it mean?
For instance, by consolidating your debt balances into one, you will improve your interest rate thanks to the credit card balance transfer. Many transfers also offer low introductory interest rates that can go all the way down to 0% APR during the first year, which can help you focus more your payments on your principal rather than interest.
If you can, do your best to pay off your debt before the introductory interest rate period lapses, because it will allow you to save on interest charges.
Move your debt to a different credit card
If you feel trapped with your current credit cards, or you are dealing with high interest rates and terms that don’t suit your needs anymore, you can always move your debt to a credit card that has a lower interest rate and more favorable terms (depending on your approved card), even a balance transfer card offering you rewards exists.
Nevertheless, wait until your transferred balance is completely paid off before you take on new credit card debt.
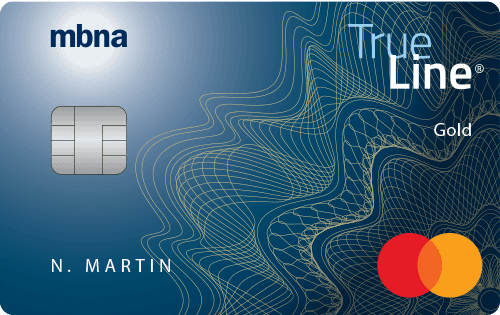
The MBNA True Line® Gold Mastercard® is MBNA’s lowest interest rate credit card.
With this card, you benefit from low rates at all times:
10.99% on purchases
13.99% on balance transfers
All for an annual fee of just $39.
It’s an ideal card for reducing interest charges if you carry a balance from month to month, while enjoying Mastercard protections like Purchase Assurance and Extended Warranty.
Legal
†, ✪, Terms and Conditions apply.
The offer does not apply to residents of Quebec.
Sponsored advertising. MBNA is a division of The Toronto-Dominion Bank (TD) and TD is not responsible for the contents of this site including any editorials or reviews that may appear on this site. For complete information about this MBNA credit card, click on the « Apply Now » button.
The Toronto-Dominion Bank is the issuer of this credit card. MBNA is a division of The Toronto-Dominion Bank.
Annual fee
Primary card$39
Additional card$0
Annual income required
Individual$0
Household$0
Conversion fees
2.5%
Earning rate
0xAll spending
Value
2nd Year Value$-39
Travel insurance
Travel AccidentIncluded
Purchase protection
Purchase ProtectionIncluded
Extended Warranty+1 years
Auto Rental CollisionIncluded
Disadvantages of balance transfers
While credit card balance transfers help individuals save significant amounts of money in many ways, it’s still crucial to identify and stay away from terms and details that may hold you back in the future.
Make sure you already have a clear plan on how you can pay off your debt with a credit card balance transfer, because it may cost you otherwise.
Balance transfer fee
Most good things are anything but free, which is the case for balance transfers!
Balance transfer fees can be charged any time you move one credit card balance to another, and these fees need to be considered before deciding whether you should transfer any balances or not. Consider that added cost before you transfer your balance to make sure you’re still saving money. Often between 3% and 5% of your transfer balance, this fee must be considered and evaluated before deciding to transfer any balances; for example, if you want to transfer a balance of $10,000 to another credit card, and the balance transfer fee is 2%, you will need to pay $200 upfront.
There are, however, some balance transfer cards that may waive this transfer fee if you complete your balance transaction within an already set period.
The low interest rate is for a limited time
While a low, introductory interest rate is an advantage of a credit card balance transfer, it can be a disadvantage because it doesn’t last forever. Balance transfer cards may offer a 0% intro APR, but only for a specific amount of time, anywhere from 6 to 21 months.
That means in case you’re using this card to pay off your debt, you should be aware of the expiration date of the promotional period, and at what level the APR will be after that.
You may not be eligible
To qualify for a credit card balance transfer, you typically need a good credit score. If not, you can still be considered but with a higher interest rate! which can make you question and reconsider the credit card balance transfer option altogether.
Replacing current debt with more debt
If you’re looking for a balance transfer, you must be hoping to get back on track, pay off your debt, and save money on interest. Credit card balance transfer agreements seduce customers with low interest rates and minimal fees in the beginning, but if you haven’t resolved the source and origin of the issue, having another credit card could easily lead to more debt.
Be conscious of the temptation to make more purchases with the new card’s appealing interest rates, and if you have chosen this method as a way to buy more items, you will end up with more debt than before!
Our valuationMilesopedia first-year estimateFirst-year valueAnnual fee rebated$29Total$29Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
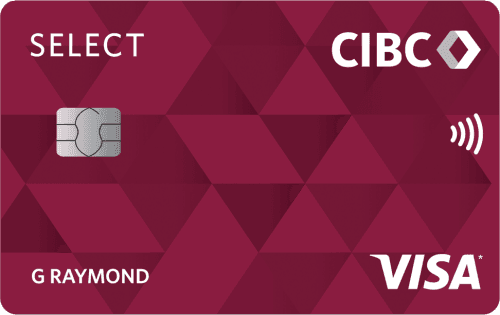
The CIBC Select Visa* Card is one of the best Visa credit cards in Canada for balance transfers.
With this exclusive digital offer for this CIBC balance transfer credit card, you get:
a 0% interest rate on balance transfers of at least $100, for up to 10 months
a refund of the annual fee for the first year†
You only pay a 1% balance transfer fee when transferring a balance from another credit card (balance transfer fees do not apply to Quebec residents). Once the promotional period ends, the card’s standard interest rate of 13.99% applies to any remaining balance. This interest rate is lower than those charged by many other credit cards.
For example, you could make large purchases on another credit card (such as renovations or furniture and appliance purchases) and then transfer the balance to the CIBC Select Visa* Card to benefit from its 0% interest rate on balance transfers for 10 months.
CIBC Select Visa* Card cardholders can also save on gas through the card’s partnership with Journie Rewards, which allows them to save up to 10 cents per litre at participating gas stations.
The CIBC Select Visa* Card has a $29 annual fee (refunded for the first year) and requires a minimum household income of $15,000 to qualify. With CIBC mobile banking and online banking services, you can easily track your credit limit and balance transfers from your phone or by signing in online.
Legal
† Terms and conditions apply. Click on Apply Now to learn more.
Annual fee
Primary card$29
Additional card$0
Annual income required
Individual$0
Household$15,000
Conversion fees
2.5%
Earning rate
0xAll spending
Value
1st Year Value$29
2nd Year Value$29
Balance transfer fee explained
Intuitively, the term refers to the amount of money charged to transfer existing debt from one financial institution to another, and this fee -usually a percentage of the total amount- is usually charged by credit card companies when balances are moved from one card to another. New customers may be offered no to low balance transfer fees as introductory offers.
As a cardholder, you should know all the fees and costs involved, and you’re the only one responsible for any charges that may occur, balance transfer fees, interests on outstanding balances, late payment fees, over-limit fees, etc.
If you want to initiate a balance transfer transaction, you need to contact the card company to where the balance will be transferred. You will be asked to share the following details:
your name
the amount transferred
your card’s account number
As mentioned before, customers often use balance transfers to move high interest debt to cards with lower interest rates, especially when there is an introductory offer involved. However, balance transfer checks can also be used for transfers or other purchases.
For example, a credit card balance of $10,000 at a 15% interest rate results in an annual interest expense of $1,500. If the credit card issuer offers a promotional interest rate of 2% for an introductory period of 12 months, with a balance transfer fee of 1%, and the deal ends up being accepted, the total cost of moving the entire amount will be around $300 (the transfer fee of $100 plus interest payments of $200). This way, $1,200 can be saved over the year.
Steps you need to come out ahead with a Balance Transfer
In order to make the most out of a credit card balance transfer, make sure to consider the following steps:
Can You Qualify? Check your credit score to ensure you qualify. You risk higher interest rates with a low credit score (less than 560), even if you manage to qualify eventually.
Review your Finances: assess your current financial situation before deciding to do a balance transfer and ask yourself the following questions: how much credit card debt you need to be transferred? What’s your current interest rate(s) and what will the transfer card interest rate be? How long do you need to pay off the balance?
Don’t forget to read the Fine Print: Always pay attention to the terms and conditions of your credit card balance transfer agreement, because some transfers –if not all- have hidden fees, lower credit limits and card restrictions, as well as and higher interest rates on new purchases.
Pay off your debt: You need to have all of your information ready for your application process, including your personal information, bank account information, and the amount of debt you are looking to transfer. Once approved, your old balance will be added to the new credit card (including the balance transfer fee).
Pay on time: If it hasn’t been stressed enough, make sure you keep track of your history payments and pay on time. Late payments will compromise your low introductory rate.
Our valuationMilesopedia first-year estimateFirst-year valueWelcome bonus$100Total$100Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
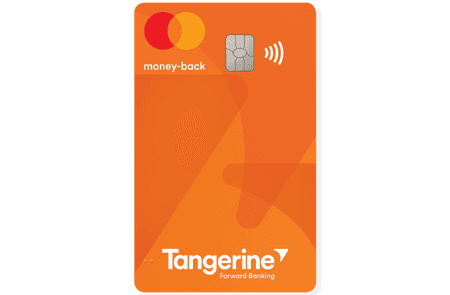
The Tangerine Money-Back Credit Card has no annual fee and offers cash back.
With this limited-time welcome offer, you can earn an additional 10% cash back (up to $100) when you spend up to $1,000 on everyday purchases during the first 2 months.
You can choose two to three purchase categories that interest you (groceries, gas, home furnishings, renovations, recurring bills, pharmacy, etc.) to earn 2% cash back ! And there’s no annual cash-back limit. It is one of the best credit cards for renovations.
In addition, the Tangerine Mastercard offers several insurance coverages for your purchases :
90 days purchase insurance
One year extended warranty
Finally, during the first 30 days you hold the card, transfer credit card balances and pay only 1.95% interest on these balances for the first 6 months.
Save on fuel with Shell
All Tangerine cardholders can get savings and rewards on fuel with Shell and Scene+ when you link your cards to your Shell Go+ account. Get up to 8¢/L in value with a linked Money-Back World Mastercard or Money-Back Credit Card:
Instant savings of 3¢ per litre on all grades of Shell fuel.
Earn up to 3¢ per litre in cash back with fuel selected as a 2% category.
Earn 1¢ per litre in Scene+ points value on all grades of Shell fuel, or 2¢ per litre in Scene+ points value on Shell V-Power® when you link your Scene+ Account to Shell Go+.
Legal
*Conditions apply.
† Bank Offer: This offer is provided by Tangerine Bank and is subject to their terms and conditions.
† Bank Offer: This offer is provided by Tangerine Bank and is subject to their terms and conditions.
Annual fee
Primary card$0
Additional card$0
Annual income required
Individual$12,000
Household$12,000
Conversion fees
2.5%
Earning rate
2xGas
2xGroceries
0.5xAll spending
Value
1st Year Value$415
2nd Year Value$246
Purchase protection
Purchase ProtectionIncluded
Extended Warranty+1 years
How to choose the right credit card for a balance transfer?
Before applying for a balance transfer, try to keep an eye on:
Promotions: If you want to pay your debt off rapidly, search for promotions; the lower the interest rate, the better!
Promotional period: Verify if the offer in front of you is long enough for you to be able to pay off the balance. Once the promotion ends, the interest rate goes back to normal, and you will need to pay higher interest rates.
Card issuer: You can’t transfer a balance to a card that’s from your same issuer. Do your research and look for the right one for you.
Credit limit: The amount you are willing to transfer depends on the card you’re moving your debt to. For some cards in Canada, the maximum amount is the actual card’s credit limit, while it can only be 50% for other cards.
Credit score: Your credit history will guarantee your qualification for the best balance transfer offers.
No interest-free grace period: Unless you managed to use a 0% interest rate offer, you will be charged interest right after the balance transfer is posted to your account
New purchases: The promotional rate agreed upon only applies to the balance you transferred, which means new purchases equal higher rates. Any payments you decide to make will go toward your balance transfer first. This means you will be charged on new purchases, which will keep adding up until you pay off your entire balance transfer
Before applying for a credit card balance transfer, find a plan that will help you pay your debt as soon as possible. Remember these three things; balance transfer fee, interest rate, and annual fee (always aim for the lowest).
Conclusion
To sum up, keep in mind that credit card companies make great offers to new and valued customers, like low-percentage introductory or teaser interest rates, which encourages new consumers to apply for cards, or to existing customers with good history track to transfer balances to them.
You are advised to look carefully at the terms before going through with an offer; the teaser rate and how long it lasts are two important things to consider.
Our valuationMilesopedia first-year estimateFirst-year valueAnnual fee rebated$29Total$29Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
The CIBC Select Visa* Card is one of the best Visa credit cards in Canada for balance transfers.
With this exclusive digital offer for this CIBC balance transfer credit card, you get:
a 0% interest rate on balance transfers of at least $100, for up to 10 months
a refund of the annual fee for the first year†
You only pay a 1% balance transfer fee when transferring a balance from another credit card (balance transfer fees do not apply to Quebec residents). Once the promotional period ends, the card’s standard interest rate of 13.99% applies to any remaining balance. This interest rate is lower than those charged by many other credit cards.
For example, you could make large purchases on another credit card (such as renovations or furniture and appliance purchases) and then transfer the balance to the CIBC Select Visa* Card to benefit from its 0% interest rate on balance transfers for 10 months.
CIBC Select Visa* Card cardholders can also save on gas through the card’s partnership with Journie Rewards, which allows them to save up to 10 cents per litre at participating gas stations.
The CIBC Select Visa* Card has a $29 annual fee (refunded for the first year) and requires a minimum household income of $15,000 to qualify. With CIBC mobile banking and online banking services, you can easily track your credit limit and balance transfers from your phone or by signing in online.
Legal
† Terms and conditions apply. Click on Apply Now to learn more.
Our valuationMilesopedia first-year estimateFirst-year valueWelcome bonus$469Annual fee rebated$120Total$589Rewards on your spending are not included. The calculator that adds them from your own profile is on the card's page.
The BMO eclipse Visa Infinite* Card is one of the best Visa Infinite rewards credit cards in Canada. Its welcome offer lets you earn up to 70,000 BMO Rewards points, for a total value of up to $1,150*.
It also includes a monthly statement credit for streaming services, an annual $50 lifestyle credit, and no annual fee for the first year (a $120 value)*.
With the BMO eclipse Visa Infinite* Card, you also get:
5x BMO Rewards points for every dollar spent on groceries, meal delivery or takeout, rideshare, public transit, and gas*
1 BMO Rewards point for every dollar spent on all other purchases*
10% more points when you add an authorized user to your account*
Mobile device insurance offering coverage up to $1,000*
The Pay with Points feature, which allows you to redeem your points on recent purchases starting at $1*
Six months of Instacart+ membership plus a monthly $10 Instacart credit with an eligible card*
Legal
*Terms and conditions apply
BMO is not responsible for updating the content of this site. For the most up-to-date information, please click on the Online Application link.
Annual fee
Primary card$120
Additional card$50
Annual income required
Individual$60,000
Household$100,000
Conversion fees
2.5%
Earning rate
5xTransit
5xGas
5xRestaurants
5xGroceries
1xAll spending
Value
1st Year Value$1,128
2nd Year Value$365
Travel insurance
Travel medical (under 55)Up to $5,000,000 / 21 days
Travel medical (55-64)Up to $5,000,000 / 21 days
Travel AccidentUp to $500,000
Purchase protection
Purchase ProtectionIncluded
Extended Warranty+1 years
Mobile DeviceUp to $1,000 / 1 years
Auto Rental CollisionUp to $65,000 / 48 days
Our editorial integrity
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.