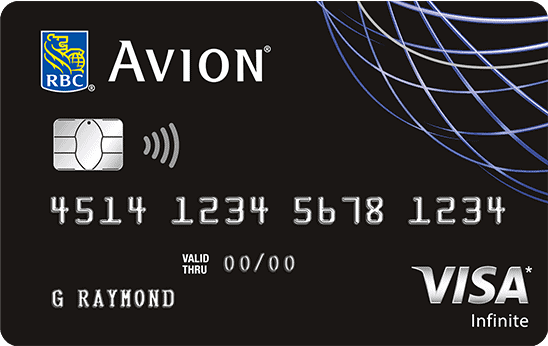
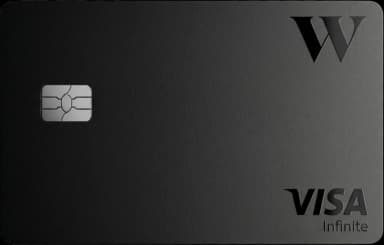
Head to Head: RBC Avion Visa Infinite vs Wealthsimple Visa Infinite+
Loading article…
Here are two Visa Infinite credit cards that reward your spending in opposite ways:
On one side, RBC pays Avion points you can redeem for flights or transfer to airline programs. On the other, Wealthsimple pays 2% cash back on everything, charges no foreign exchange fees, and waives its annual fee for part of its client base. The RBC Avion vs Wealthsimple question therefore comes down to one thing: are Avion points worth RBC's $120 annual fee? If you are weighing other cards, our comparisons of RBC Avion vs TD Aeroplan and Wealthsimple vs Scotiabank Passport round out the picture, as does our list of the best credit cards in Canada.
| Credit card | Annual fee | Welcome offer | |
|---|---|---|---|
| $120 | |||
| $240 |
We base our analysis on the major differences between these two credit cards:
Here are both cards side by side, as of October 20, 2026. We then break down each line.
| Criteria | RBC Avion Visa Infinite Card | Wealthsimple Visa Infinite+ Card |
|---|---|---|
| Annual fee | $120 | $240 ($20 a month), waived under conditions |
| Additional card | $50 | Not specified |
| Minimum income | $60,000 personal or $100,000 household | $80,000 personal or $150,000 household |
| Rewards | Avion points: 1.25 pt/$ on travel; 1 pt/$ elsewhere | 2% cash back on everything |
| Foreign exchange fee | 2.5% | None |
| Welcome bonus | Up to 70,000 Avion points, until November 25, 2026 | 5% on $10,000 over 35 days, so up to $500 (new clients) |
| Emergency medical | No claim maximum, 15 days (3 days at 65 and over) | $1,000,000, 14 days |
| Rental car coverage | Yes, up to $65,000 | No |
| Airport lounges | No access | No access |
| Milesopedia valuation | 1.7 cents per point | Cash back ($1 = $1) |
These two offers do not play in the same league. RBC pays points over a year; Wealthsimple boosts your cash back for five weeks.
The RBC Avion Visa Infinite Card offers up to 70,000 Avion points:
The Wealthsimple Visa Infinite+ Card, for its part, gives new clients a total of 5% cash back for the 35 days after approval:
Wealthsimple's conditions are tight. The offer targets new clients invited by email or in the app who have never held a Wealthsimple credit card. The card must also stay open for 180 days after the boosted period, or the boost can be clawed back.
At Milesopedia valuations, the gap is clear. The 70,000 Avion points are worth about $1,190 at 1.7 cents per point, against a Wealthsimple boost of $300 at most.
This is where the Wealthsimple card claws back ground. Its earning grid fits in one number, while RBC only boosts travel.
The RBC Avion Visa Infinite Card earns 1.25 Avion points per dollar on eligible travel purchases and 1 point per dollar on everything else. No everyday category gets a boost.
The Wealthsimple Visa Infinite+ Card pays 2% cash back on every purchase, with no categories to track and no annual cap. You can redeem it at any time to almost any Wealthsimple account.
An earn rate means nothing without the point value. Milesopedia values the Avion point at 1.7 cents. Here is the return in cents per dollar spent.
| Type of spending | RBC Avion Visa Infinite Card | Wealthsimple Visa Infinite+ Card |
|---|---|---|
| Eligible travel purchases | 1.25 pt/$, or 2.13 cents/$ | 2%, or 2.00 cents/$ |
| Groceries, gas, dining and everything else | 1 pt/$, or 1.70 cents/$ | 2%, or 2.00 cents/$ |
| Everyday purchase in a foreign currency, after FX fees | 1.70 cents/$ minus 2.5%, or -0.80 cents/$ | 2.00 cents/$, no fees |
| Points redeemed through the RBC fixed chart (35,000 points for a flight up to $750) | 1 pt/$, or up to 2.14 cents/$ | Not applicable |
This line changes everything for travellers. The RBC card charges a 2.5% foreign exchange fee on every purchase in a foreign currency. Wealthsimple charges none.
Take a $100 meal paid in euros:
Our ranking of the best no foreign transaction fee cards lists other options.
The Wealthsimple Visa Infinite+ Card carries a $240 annual fee, billed at $20 a month, according to Wealthsimple's official card page. In Quebec, Wealthsimple bills it once a year instead.
Wealthsimple waives that fee in two cases:
If you meet neither condition, the card costs twice as much as the RBC card. That is the pivot of this whole comparison.
To answer, we calculated each card's net annual gain, after the annual fee and excluding the welcome bonus. We test two Avion point values: our 1.7 cent valuation and RBC's fixed redemption chart.
RBC does publish a fixed chart for air travel rewards. Under its terms, a round trip almost anywhere in Canada or the United States with a fare up to $750 costs 35,000 Avion points, or 2.14 cents per point if you use the full cap. Taxes and surcharges stay on you. Our breakdown of the value of RBC Avion points covers every scenario.
| Annual spending | RBC Avion at 1.7 cents | RBC Avion via chart (2.14 cents) | Wealthsimple, fee waived | Wealthsimple, $240 fee |
|---|---|---|---|---|
| $15,000 | $135 | $201 | $300 | $60 |
| $30,000 | $390 | $522 | $600 | $360 |
| $50,000 | $730 | $950 | $1,000 | $760 |
Three takeaways come out of the math:
In short, Avion points are worth the annual fee if you would pay Wealthsimple's fee, or if you travel enough to use the chart. If your Wealthsimple fee is waived, 2% cash back pays more from year two onward.
Avion points give you several exits. You can book a flight on more than 500 airlines with no blackout periods, use the fixed chart, or transfer to American Airlines AAdvantage, The British Airways Club, Cathay Pacific Asia Miles and WestJet Rewards. Simple conversion to cash, however, is worth only 1 cent per point according to RBC: 100 points for $1.
Those options take some effort. The Avion Rewards program page explains the membership tiers and transfer rules.
Wealthsimple cash back takes no effort at all. You deposit it into your Wealthsimple chequing account, where it can earn up to 2.25% interest according to Wealthsimple, or into a Wealthsimple TFSA or RRSP.
Both cards carry the same purchase interest rate, 20.99%. Everything else differs.
The RBC Avion Visa Infinite Card:
The Wealthsimple Visa Infinite+ Card:
The RBC card offers the more complete package. Its emergency medical coverage has no claim maximum and covers 15 days, or 3 days from age 65. It adds rental car collision coverage up to $65,000 for 48 days, hotel burglary and travel accident insurance.
The Wealthsimple card covers emergency medical up to $1,000,000. It beats RBC on trip cancellation and baggage, but offers no rental car coverage. Here is the detail.
| Coverage | RBC Avion Visa Infinite Card | Wealthsimple Visa Infinite+ Card |
|---|---|---|
| Emergency medical | No claim maximum, 15 days (3 days at 65 and over) | Up to $1,000,000, 14 days |
| Trip cancellation | $1,500 | Up to $3,000 per trip (cancellation and interruption) |
| Trip interruption | $5,000 | Included in the $3,000 limit |
| Delayed and lost baggage | $500 and $500 | $1,000 per trip |
| Flight delay | $500 | Included (amount in the certificate) |
| Travel accident | $500,000 | Not listed |
| Rental car | Up to $65,000, 48 days | Not offered |
| Hotel burglary | $2,500 | Not listed |
| Mobile device | $1,500 | $1,000 |
| Purchase protection and extended warranty | 90 days and 1 year | 90 days (up to $1,000 per claim) and extended warranty |
Neither card grants airport lounge access. Wealthsimple keeps that perk for its Visa Infinite Privilege.
The RBC card leans on its partners: 3 cents off per litre at Petro-Canada with 20% more Petro-Points and Avion points, 50 Be Well points per dollar at Rexall, 12 months of DashPass and Hertz privileges.
The Wealthsimple card adds a 24/7 concierge, Visa Infinite benefits, GigSky data plans and no tap limit on the virtual card. Clients with more than $100,000 in assets get a metal card.
One answer does not fit everyone. Here are three distinct profiles.
You hold more than $100,000 in assets at Wealthsimple, or your paycheque already lands there. In that case, the Wealthsimple Visa Infinite+ Card wins from year two. It costs you nothing, pays 2% everywhere and charges no FX fees.
You want a specific flight, a transfer to Avios or Asia Miles, or a predictable chart. In that case, the RBC Avion Visa Infinite Card serves you better. Its 70,000-point bonus already funds a trip, and the fixed chart pushes the point value past 2 cents.
You refuse to pay an annual fee. The Wealthsimple card fits, but only if you reach the asset threshold or the $4,000 monthly direct deposit. Otherwise it costs $240, and neither card is right for you. See our ranking of the best cash back credit cards instead.
So which card wins this duel? The answer depends first on your relationship with Wealthsimple. With the fee waived, the Wealthsimple Visa Infinite+ Card wins over the long run: 2%, everywhere, with no FX fees.
The RBC Avion Visa Infinite Card still holds two strong cards, though. Its 70,000-point bonus is worth about $1,190, nearly four times the Wealthsimple boost. Its insurance also covers more situations, including car rentals.
Finally, nothing forces you to choose. The two cards come from different issuers: plenty of readers keep the Wealthsimple card for foreign purchases and the RBC card to collect Avion points. For more detail, read our review of the Wealthsimple cards and the RBC Avion Visa Infinite Card page.
To catch offers like these as they land, subscribe to our newsletter.
| Credit card | Annual fee | Welcome offer | |
|---|---|---|---|
| $120 | |||
| $240 |
Here are frequently asked questions from the Milesopedia community about these two cards.
The RBC Avion Visa Infinite Card leads clearly with up to 70,000 Avion points, for applications submitted by November 25, 2026. At 1.7 cents per point, that comes to about $1,190. The Wealthsimple Visa Infinite+ Card offers 5% cash back on the first $10,000 over 35 days, so $500 at most, of which the real boost is $300. Full terms are on the Wealthsimple card page.
Wealthsimple automatically waives the $240 fee for its Premium and Generation clients, meaning those with more than $100,000 in individual assets. Core clients also get the waiver if they receive at least $4,000 a month by direct deposit into a Wealthsimple chequing account. Without one of those conditions, you pay $20 a month, or one annual charge in Quebec.
Not always. At our 1.7 cent valuation, one Avion point per dollar returns 1.7%, below Wealthsimple's 2%. Avion points only beat cash back through RBC's fixed chart, which reaches 2.14 cents per point on a $750 flight within North America. Our breakdown of the value of RBC Avion points lays out every scenario.
The Wealthsimple Visa Infinite+ Card, without question. It charges no foreign exchange fees and pays 2% on purchases in a foreign currency. The RBC Avion Visa Infinite Card charges a 2.5% FX fee, which wipes out the value of the points you earn. Our ranking of no foreign transaction fee cards lists other choices.
For emergency medical, the RBC card dominates: no claim maximum, 15 days of coverage, and 3 days from age 65. It also adds rental car collision coverage. The Wealthsimple card does offer higher limits for trip cancellation, up to $3,000 per trip, and for baggage, at $1,000 per trip.
The RBC Avion Visa Infinite Card requires a personal income of $60,000 or a household income of $100,000. The Wealthsimple Visa Infinite+ Card asks for more: $80,000 personal or $150,000 household, plus an active Wealthsimple chequing account. Wealthsimple also notes that the card is available in limited quantities.
Yes, since the two cards come from different issuers. A logical setup is to use the Wealthsimple card for foreign currency purchases and everyday spending, then the RBC card for travel purchases in Canada. You collect both welcome bonuses that way, as long as you meet each spending threshold.
on RBC's website
Our reviews and rankings are based on an objective assessment. Advertisers do not influence our content. We may receive compensation through some links; our analysis and opinions remain independent.